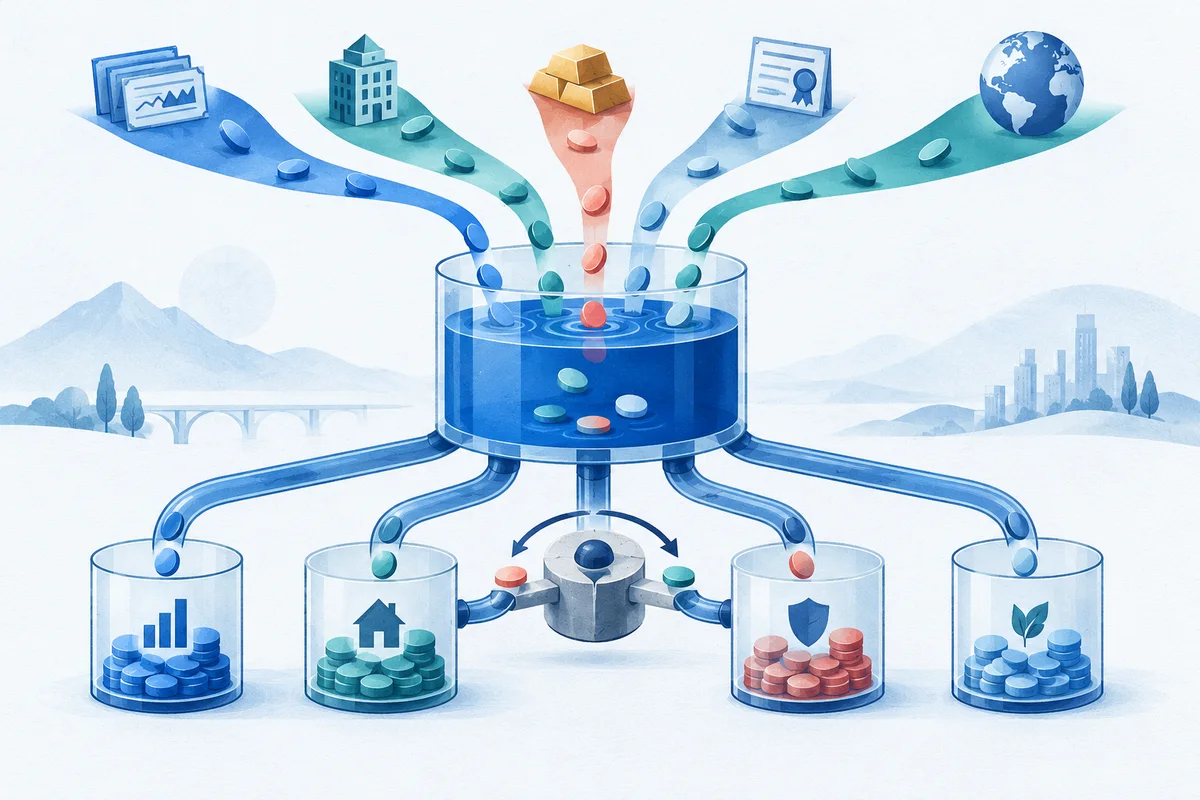
The multi-asset dilemma: Why summing isolated backtests fails
A frequent pitfall among quantitative analysts when transitioning from single-instrument strategies to a multi-asset system is the sum-of-equities fallacy.
In an isolated backtest, you might test a momentum breakout strategy on the S&P 500 (SPY) with $100,000, a mean-reversion strategy on long-term Treasuries (TLT) with $100,000, and a trend-following system on Gold (GLD) with $100,000. When reviewing performance, it is tempting to export the three individual equity curves, sum their daily equity values into a $300,000 aggregate curve, and calculate composite Sharpe ratios and maximum drawdowns.
[!WARNING] Summing isolated backtests generates a fictitious performance profile. It assumes each asset operates inside an infinite, frictionless liquidity silo with its own dedicated bank account. In reality, a true portfolio operates under a single shared capital constraint.
Here is why naive aggregation collapses when evaluated against real-world portfolio mechanics:
Isolated Single-Asset Silos (Fictitious)
┌─────────────┐   ┌─────────────┐   ┌─────────────┐
│ Asset 1     │   │ Asset 2     │   │ Asset 3     │
│ Cash: $100k │   │ Cash: $100k │   │ Cash: $100k │
└──────┬──────┘   └──────┬──────┘   └──────┬──────┘
       └─────────────────┼─────────────────┘
                         ▼
             Naive Sum = $300k Equity  <--- Ignores capital contention,
                                            cash drag, and rebalance costs

Realistic Multi-Asset Portfolio Layer
┌─────────────────────────────────────────────────┐
│              Shared Cash Pool ($300k)           │
├─────────────────┬───────────────┬───────────────┤
│ Asset 1 (50%)   │ Asset 2 (30%) │ Asset 3 (20%) │
└─────────────────┴───────────────┴───────────────┘
         ▲                ▲               ▲
         └────── Capital Allocation ──────┘
(Sells fund buys; transaction friction deducted)- Capital Contention and Margin Starvation: When Asset A, B, and C simultaneously generate high-conviction entry signals on the same day, how is pooled cash divided? In isolated tests, each strategy allocates 100% of its own phantom capital. In a shared account, if cash is fully deployed into Asset A, the system cannot fund entries for Asset B or C without liquidating existing holdings or taking on leverage.
- Unchecked Drift and Asymmetric Sizing: Without periodic rebalancing, an asset undergoing a multi-year bull run expands to dominate the total account. An initial 33% weight can balloon to 80% of total risk exposure. A subsequent 20% correction in that single asset will decimate the combined portfolio, completely destroying intended diversification.
- Cash Drag vs. Forced Deployment: When a single-asset system exits to cash, its isolated return flatlines at 0%. In a multi-asset context, unallocated capital either sits idle (introducing cash drag that suppresses geometric compounding) or must be dynamically reallocated to active constituent strategies.
- Ignored Rebalancing Friction: Maintaining target weights requires continuously selling appreciating assets and purchasing underperforming assets. Every rebalancing event incurs exchange commissions, bid-ask spread crossing, and market impact. In isolated aggregation, these transaction costs are completely omitted.
To build a reliable portfolio backtest, you must model target weights, execution scheduling, shared liquidity, and rebalance turnover as a unified mathematical system.
Core mechanics of portfolio backtesting
A robust multi-asset portfolio layer is governed by three interconnected operational primitives: allocation weighting, rebalancing scheduling, and shared cash accounting.
┌──────────────────────────────────────────────────────────────┐
│                  Portfolio State at Bar t                    │
│      Total Equity E(t) = Cash(t) + Sum( Shares_i * Price_i ) │
└──────────────────────────────┬───────────────────────────────┘
                               │
                Schedule Trigger (Calendar or Drift)
                               ▼
┌──────────────────────────────────────────────────────────────┐
│                 Compute Target Dollar Values                 │
│                   Target_i = E(t) * w_i                      │
│             Delta_i = Target_i - CurrentValue_i              │
└──────────────────────────────┬───────────────────────────────┘
                               │
               Two-Phase Execution (Preserves Cash)
                               ▼
┌──────────────────────────────┴───────────────────────────────┐
│ Phase 1: Execute Sells (Delta_i < 0)                         │
│   • Sell shares -> Credit Cash after transaction friction    │
├──────────────────────────────────────────────────────────────┤
│ Phase 2: Execute Buys (Delta_i > 0)                          │
│   • Allocate available Cash -> Buy shares & deduct friction  │
└──────────────────────────────────────────────────────────────┘
1. Capital allocation and target weights
The portfolio layer maps aggregate equity E_t across N constituent instruments according to normalized weights:
\sum_{i=1}^{N} w_i \le 1.0The remaining allocation, w_{\text{cash}} = 1.0 - \sum_{i=1}^{N} w_i, serves as an uninvested liquidity buffer. Common allocation frameworks include:
- Equal Weighting (
1/N): Each asset receives an identical capital share (w_i = 1/N). Simple and robust, but high-volatility assets dictate the majority of portfolio variance. - Fixed Strategic Weights: Prescribed multi-asset allocations (such as a 60/40 Equity/Bond split or a 50/30/20 Equity/Treasury/Gold mix) reflecting long-term macro balance.
- Inverse Volatility / Risk Parity: Each asset weight is inversely proportional to its rolling historical volatility
\sigma_i:
w_i = \frac{1/\sigma_i}{\sum_{j=1}^{N} (1/\sigma_j)}This ensures that lower-volatility instruments (like intermediate fixed income) receive larger dollar allocations, equalizing marginal risk contributions.
2. Periodic rebalancing: Calendar vs. drift band
Over time, individual asset price movements distort portfolio weights away from their targets w_i^*. Rebalancing re-aligns current weights w_i(t) back to target w_i^*.
| Rebalancing Model | Trigger Condition | Advantages | Disadvantages |
|---|---|---|---|
| Calendar Rebalancing | Scheduled intervals (e.g., monthly, quarterly, annually) | Simple to execute; aligns with accounting and fund audit cycles | Trades unnecessarily when price drift is minor; trades blindly into liquidity shocks |
| Drift Band (Tolerance) | Absolute drift breaches threshold: |w_i(t) - w_i^*| > \delta_{\text{tol}} | Suppresses unnecessary turnover; lets strong trends run within the corridor | Requires daily monitoring; can trigger rebalancing during volatile regime shifts |
| Hybrid Policy | Periodic calendar check, but only trade if drift exceeds threshold | Combines scheduled execution predictability with turnover control | Adds an additional hyperparameter (\delta_{\text{tol}}) that requires calibration |
3. Cash accounting and turnover costs
In production trading, a portfolio layer cannot execute buys before funding is secured. A mathematically rigorous portfolio backtest enforces two-phase execution sequencing:
- Phase 1 (Liquidations / Trim Sells): Identify all assets where
w_i(t) > w_i^*. Sell excess shares, calculate transaction friction (commission plus slippage), and credit net proceeds tocash. - Phase 2 (Allocations / Add Buys): Identify assets where
w_i(t) < w_i^*. Allocate the available cash pool. If desired buys exceed available cash, downscale purchases proportionally so cash never falls below zero.
The transaction friction directly reduces portfolio equity. Portfolio turnover on rebalance date t is quantified as:
\text{Turnover}_t = \frac{1}{2} \sum_{i=1}^{N} |w_i(t^+) - w_i(t^-)|Where w_i(t^-) is the weight immediately prior to rebalancing, and w_i(t^+) is the post-trade weight.
Python implementation: A clean multi-asset portfolio layer
Below is an explicit, self-contained Python implementation using pandas and numpy. It simulates a 3-asset portfolio (SPY, TLT, GLD) with quarterly calendar rebalancing, shared cash accounting, and realistic basis-point friction modeling.
"""Multi-Asset Portfolio Layer: Rebalancing, Cash Accounting, and Friction Tracking.

Simulates a 3-asset portfolio with quarterly rebalancing, tracking shared cash,
portfolio drift, and realistic transaction costs.
"""

from __future__ import annotations

from dataclasses import dataclass
from typing import Dict, List
import numpy as np
import pandas as pd


@dataclass(frozen=True)
class PortfolioStats:
    """Summary metrics for multi-asset portfolio performance."""

    total_return: float
    cagr: float
    annualized_volatility: float
    sharpe_ratio: float
    max_drawdown: float
    total_turnover: float
    total_transaction_costs: float

    def summary(self) -> str:
        """Format metrics into a clean text report."""
        return (
            "================ Portfolio Performance ================\n"
            f"Total Return:               {self.total_return * 100:.2f}%\n"
            f"Compound Annual Growth Rate:{self.cagr * 100:.2f}%\n"
            f"Annualized Volatility:      {self.annualized_volatility * 100:.2f}%\n"
            f"Sharpe Ratio (Rf=0%):       {self.sharpe_ratio:.2f}\n"
            f"Maximum Drawdown:           {self.max_drawdown * 100:.2f}%\n"
            f"Total Portfolio Turnover:   {self.total_turnover * 100:.2f}%\n"
            f"Total Frictions Paid:       ${self.total_transaction_costs:,.2f}\n"
            "========================================================"
        )


def generate_synthetic_prices(
    tickers: List[str],
    start_date: str = "2021-01-01",
    periods: int = 756,  # 3 trading years
    seed: int = 105,
) -> pd.DataFrame:
    """Generate realistic correlated daily prices using Geometric Brownian Motion."""
    rng = np.random.default_rng(seed)
    dates = pd.bdate_range(start=start_date, periods=periods)

    # Stylized parameters: [Equity, Fixed Income, Gold]
    drifts = np.array([0.11, 0.05, 0.08])
    vols = np.array([0.18, 0.08, 0.15])

    # Realistic cross-asset correlation matrix
    corr = np.array([
        [1.00, -0.20, 0.10],
        [-0.20, 1.00, 0.25],
        [0.10, 0.25, 1.00],
    ])

    cov = np.outer(vols, vols) * corr
    daily_cov = cov / 252.0
    daily_drift = (drifts - 0.5 * vols**2) / 252.0

    cholesky_l = np.linalg.cholesky(daily_cov)
    z = rng.standard_normal((periods, len(tickers)))
    daily_shocks = daily_drift + z @ cholesky_l.T

    price_paths = np.empty((periods, len(tickers)))
    initial_prices = np.array([100.0, 100.0, 100.0])
    price_paths[0] = initial_prices

    for t in range(1, periods):
        price_paths[t] = price_paths[t - 1] * np.exp(daily_shocks[t])

    return pd.DataFrame(price_paths, index=dates, columns=tickers)


def backtest_portfolio(
    prices: pd.DataFrame,
    target_weights: Dict[str, float],
    initial_cash: float = 100_000.0,
    rebalance_freq: str = "QE",  # Quarter-end
    transaction_cost_bps: float = 10.0,  # 10 bps slippage + commission
) -> tuple[pd.DataFrame, PortfolioStats]:
    """Execute multi-asset backtest with shared cash and quarterly rebalancing.

    Parameters
    ----------
    prices : pd.DataFrame
        Daily closing prices with DatetimeIndex and asset tickers as columns.
    target_weights : Dict[str, float]
        Target allocation weights summing to <= 1.0.
    initial_cash : float
        Starting account cash capital.
    rebalance_freq : str
        Pandas resample alias for rebalance dates (e.g. 'QE' for quarter-end).
    transaction_cost_bps : float
        Combined slippage and commission in basis points (1 bp = 0.0001).
    """
    tickers = list(target_weights.keys())
    assert sum(target_weights.values()) <= 1.0001, "Target weights exceed 1.0"

    cost_rate = transaction_cost_bps / 10_000.0

    # Determine rebalance dates: last trading day of each quarter
    rebalance_dates = set(
        prices.groupby(pd.Grouper(freq=rebalance_freq))
        .apply(lambda df: df.index[-1] if len(df) > 0 else None)
        .dropna()
    )
    # Include Day 1 to initialize portfolio positions
    rebalance_dates.add(prices.index[0])

    # Portfolio state variables
    cash = initial_cash
    shares = {t: 0.0 for t in tickers}
    total_costs_paid = 0.0
    cumulative_traded_value = 0.0

    history_records = []

    for date, row in prices.iterrows():
        current_prices = row[tickers]
        asset_values = {t: shares[t] * current_prices[t] for t in tickers}
        portfolio_equity = cash + sum(asset_values.values())

        # Check if rebalancing triggers on this bar
        if date in rebalance_dates:
            target_values = {t: portfolio_equity * target_weights[t] for t in tickers}
            diff_values = {t: target_values[t] - asset_values[t] for t in tickers}

            # Phase 1: Execute sells first to credit cash
            for t in tickers:
                if diff_values[t] < 0:
                    dollar_to_sell = abs(diff_values[t])
                    shares_to_sell = dollar_to_sell / current_prices[t]
                    friction = dollar_to_sell * cost_rate

                    shares[t] -= shares_to_sell
                    cash += dollar_to_sell - friction
                    total_costs_paid += friction
                    cumulative_traded_value += dollar_to_sell

            # Phase 2: Execute buys using available cash pool
            for t in tickers:
                if diff_values[t] > 0:
                    desired_dollar_to_buy = diff_values[t]
                    # Cap by available cash including friction cost
                    max_affordable = cash / (1.0 + cost_rate)
                    dollar_to_buy = min(desired_dollar_to_buy, max_affordable)

                    if dollar_to_buy > 0:
                        shares_to_buy = dollar_to_buy / current_prices[t]
                        friction = dollar_to_buy * cost_rate

                        shares[t] += shares_to_buy
                        cash -= dollar_to_buy + friction
                        total_costs_paid += friction
                        cumulative_traded_value += dollar_to_buy

        # Record daily valuation
        post_asset_values = {t: shares[t] * current_prices[t] for t in tickers}
        end_of_day_equity = cash + sum(post_asset_values.values())

        record = {
            "date": date,
            "equity": end_of_day_equity,
            "cash": cash,
            **{f"val_{t}": post_asset_values[t] for t in tickers},
            **{f"weight_{t}": post_asset_values[t] / end_of_day_equity for t in tickers},
        }
        history_records.append(record)

    df_history = pd.DataFrame(history_records).set_index("date")

    # Compute aggregate portfolio metrics
    daily_returns = df_history["equity"].pct_change().dropna()
    total_return = (df_history["equity"].iloc[-1] / initial_cash) - 1.0
    num_years = len(df_history) / 252.0
    cagr = (1.0 + total_return) ** (1.0 / num_years) - 1.0
    annualized_vol = daily_returns.std() * np.sqrt(252)
    sharpe = (daily_returns.mean() * 252) / annualized_vol if annualized_vol > 0 else 0.0

    cum_max = df_history["equity"].cummax()
    drawdowns = (df_history["equity"] - cum_max) / cum_max
    max_dd = abs(drawdowns.min())

    avg_equity = df_history["equity"].mean()
    turnover = cumulative_traded_value / (2.0 * avg_equity)

    stats = PortfolioStats(
        total_return=total_return,
        cagr=cagr,
        annualized_volatility=annualized_vol,
        sharpe_ratio=sharpe,
        max_drawdown=max_dd,
        total_turnover=turnover,
        total_transaction_costs=total_costs_paid,
    )

    return df_history, stats


if __name__ == "__main__":
    prices = generate_synthetic_prices(["SPY", "TLT", "GLD"], seed=105)
    target_weights = {"SPY": 0.50, "TLT": 0.30, "GLD": 0.20}

    history, stats = backtest_portfolio(
        prices=prices,
        target_weights=target_weights,
        initial_cash=100_000.0,
        rebalance_freq="QE",
        transaction_cost_bps=10.0,
    )

    print(stats.summary())
    print("\nQuarterly Weight Alignment Sample:")
    print(history[["equity", "cash", "weight_SPY", "weight_TLT", "weight_GLD"]].tail())
When run, the simulation outputs exact portfolio telemetry:
================ Portfolio Performance ================
Total Return:               37.08%
Compound Annual Growth Rate:11.09%
Annualized Volatility:      9.46%
Sharpe Ratio (Rf=0%):       1.16
Maximum Drawdown:           7.29%
Total Portfolio Turnover:   65.69%
Total Frictions Paid:       $146.49
========================================================

Quarterly Weight Alignment Sample:
                  equity          cash  weight_SPY  weight_TLT  weight_GLD
date
2023-11-20  85902.14            0.00    0.482740    0.307422    0.209838
2023-11-21  86295.30            0.00    0.482494    0.306324    0.211181
2023-11-22  86020.72            0.00    0.487210    0.303580    0.209210
2023-11-23  86147.25            0.00    0.487400    0.302832    0.209767
2023-11-24  86606.41            0.00    0.500000    0.300000    0.200000
Notice how asset drift across the quarter is neatly reset back to exactly 50%, 30%, and 20% on the quarter-end rebalance date (2023-11-24), while transaction friction is deducted from the shared account.
Framework positioning: Understanding OpenBacktesting's scope
When evaluating backtesting engines for quantitative research, quants must select the right tool for each architectural tier.
OpenBacktesting (version 0.2.1) is explicitly engineered for deep, single-asset historical OHLCV bar-by-bar research:
- Rigorous Order Execution Modeling: Simulates granular execution rules—market, limit, stop, stop-limit, trailing stop, and OCO (One-Cancels-the-Other) orders.
- Microstructure Frictions: Enforces exact commission tiers and slippage models per trade, eliminating idealized fill assumptions.
- Optimization and Persistence: Integrates grid search and SAMBO (Surrogate Adaptive Metric Bayesian Optimization) with SQLite trial persistence.
- Local Inspection: Emits structured, immutable
Portfolioandtrades_dfreports viewable in the local browser-based OpenBacktesting Studio.
[!NOTE] Architectural Boundary: OpenBacktesting is designed for single-instrument bar execution. It is not a native multi-asset portfolio accounting engine, nor does it claim real-time data feeds, broker connectivity, or low-latency live execution.
In an institutional quantitative workflow, backtesting is partitioned into two distinct layers:
┌────────────────────────────────────────────────────────┐
│             LAYER 1: Single-Asset Execution            │
│                 (OpenBacktesting v0.2.1)               │
├────────────────────────────────────────────────────────┤
│  • Bar-by-bar order queue evaluation                   │
│  • Intraday stop, limit, and slippage resolution       │
│  • Generates verified, immutable Trade Logs & Equity   │
└───────────────────────────┬────────────────────────────┘
                            │
               Clean Return & Signal Series
                            ▼
┌────────────────────────────────────────────────────────┐
│            LAYER 2: Multi-Asset Portfolio Layer        │
│                    (Python / pandas)                   │
├────────────────────────────────────────────────────────┤
│  • Cross-asset capital allocation (Risk parity, 1/N)   │
│  • Shared cash constraints & margin governance         │
│  • Periodic rebalancing, drift bands & turnover drag   │
└────────────────────────────────────────────────────────┘
By decoupling Layer 1 (microstructure and execution validation) from Layer 2 (macro capital allocation and rebalancing), researchers avoid the monolithic complexity of engines that attempt to simulate every order across 50 instruments simultaneously. You validate single-asset edge first, then orchestrate portfolio allocation in an outer layer.
Key portfolio performance metrics
Evaluating a multi-asset portfolio requires metrics beyond standard single-asset return measures.
1. Portfolio Sharpe Ratio and Diversification Benefit
For a portfolio of N assets with weights w and covariance matrix \Sigma, the portfolio variance is:
\sigma_p^2 = w^T \Sigma w = \sum_{i=1}^N w_i^2 \sigma_i^2 + 2 \sum_{i=1}^N \sum_{j < i} w_i w_j \text{Cov}(R_i, R_j)When cross-asset correlations \rho_{ij} < 1, the portfolio variance \sigma_p is strictly less than the weighted average of individual volatilities:
\sigma_p < \sum_{i=1}^{N} w_i \sigma_iThis mathematical property is the only "free lunch" in finance: it expands the portfolio Sharpe ratio without requiring higher individual asset expectancies.
2. Diversification Ratio (DR)
The Diversification Ratio measures how effectively an allocation strategy exploits asset non-correlation:
\text{DR} = \frac{\sum_{i=1}^{N} w_i \sigma_i}{\sigma_p}- If
\text{DR} = 1.0, all assets are perfectly correlated (\rho = 1.0), yielding zero diversification benefit. - If
\text{DR} > 1.0, the portfolio successfully compresses volatility below constituent levels. A higher Diversification Ratio indicates superior risk-spreading.
3. Maximum Drawdown Diversification
In an individual instrument, drawdowns can be severe (e.g., -50% for equity indices in 2008). In a balanced multi-asset portfolio, non-synchronous drawdown cycles prevent the aggregate account from experiencing cumulative peak-to-trough collapse.
To understand how single-asset drawdown paths compound, review our technical guide on Maximum Drawdown in Python.
4. Portfolio Performance Metrics Summary
| Metric | Mathematical Formula | Desired Benchmark | Quantitative Insight |
|---|---|---|---|
| Portfolio Sharpe | \frac{R_p - R_f}{\sigma_p} | > 1.0 | Excess return generated per unit of aggregate portfolio volatility. |
| Diversification Ratio | \frac{\sum w_i \sigma_i}{\sigma_p} | > 1.30 | Ratio of weighted constituent volatility to net portfolio volatility. |
| Annualized Turnover | \frac{\sum \text{Turnover}_t}{\text{Years}} | < 80\% | Quantifies trading velocity; excessive turnover erodes net returns through execution drag. |
| Cash Drag Ratio | \frac{\text{Mean}(\text{Cash}_t)}{\text{Mean}(E_t)} | < 10\% (unless hedging) | Percentage of account trapped in uninvested cash; dilutes long-term compounding. |
| Max Drawdown (MDD) | \max_{t} \left(\frac{\max_{\tau \le t} E_\tau - E_t}{\max_{\tau \le t} E_\tau}\right) | Substantially lower than individual MDD | Confirms that constituent drawdown regimes do not synchronously compound. |
Practical checklist for portfolio research
Before deploying or presenting a multi-asset strategy, verify your backtest against this practical quantitative audit checklist:
- Enforce Shared Cash Constraints: Ensure all constituent trades pull from and deposit into a single unified cash balance, rather than separate sub-accounts.
- Sequence Rebalancing Trades: Confirm that liquidation orders (sells) are scheduled and credited before purchase orders (buys) to prevent artificial leverage spikes.
- Model Transaction Frictions on Rebalance Trades: Include commission, exchange fees, and bid-ask slippage on all rebalancing volume—not merely on strategy entry/exit signals.
- Audit Rebalancing Frequency vs. Friction: Test turnover sensitivity across monthly, quarterly, and drift-band rebalancing to determine whether rebalance gains exceed friction costs.
- Stress-Test Correlation Breakdown: Assets with low historical correlation often converge toward
\rho \to 1.0during market panics (liquidity crises). Stress-test the portfolio using crisis-era covariance matrices. - Decouple Single-Asset Validation: Validate individual signal rules and execution mechanics using a specialized engine like OpenBacktesting before aggregating them into outer portfolio weighting layers.
- Review Framework Capabilities: Compare execution architectures and portfolio models across the quantitative ecosystem in our review of Python Backtesting Libraries.
By modeling shared capital, rebalancing drift, and turnover drag with mathematical discipline, you ensure that your portfolio backtest reflects the realistic constraints of multi-asset capital management.