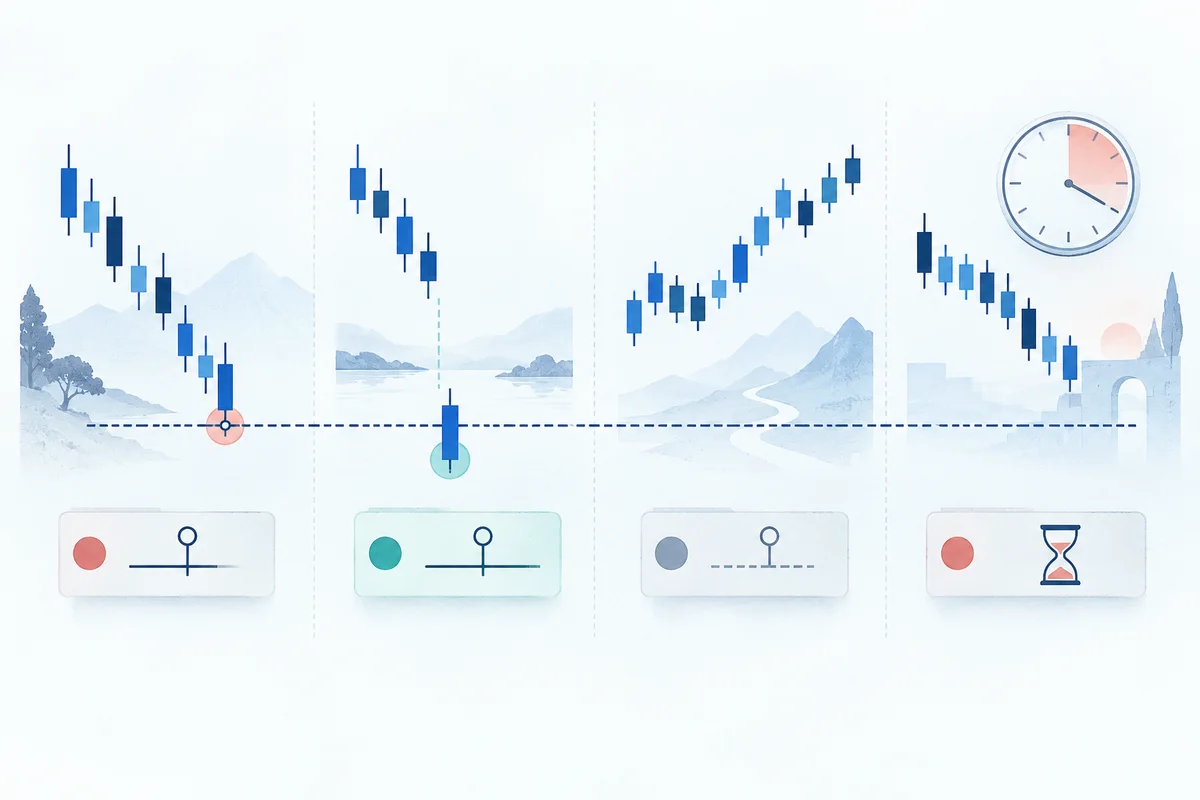
The mechanics of limit order matching in backtesting
In quantitative trading, a limit order is an instruction to execute a transaction only at a specified target price or better. For a long entry, a trader submits a buy limit order below the current market price, seeking to accumulate assets on a pullback. For an exit or short entry, a trader places a sell limit order above the market, demanding a liquidity premium.
While live limit orders rest inside an exchange's central limit order book (CLOB) governed by strict price-time priority (FIFO) queues and microsecond-level order matching, historical backtesting engines operate in a fundamentally different regime. In a discrete bar-based environment (such as daily or hourly OHLC bars), the engine receives only four price points per interval: Open, High, Low, and Close. The simulator must deduce whether, when, and at what price a resting limit order would have executed during that elapsed interval.
Backtrader addresses this simulation challenge through a deterministic set of matching rules embedded inside its broker implementation (bbroker.py). However, subtle details in Backtrader's limit order logic—such as automatic price improvement on opening gaps, optimistic assumptions on intrabar price touches, and quirky order validity expiration rules—frequently introduce hidden biases or unexpected strategy behaviors.
Unlike multi-order structures like Backtrader bracket orders, where child orders remain dormant until a parent order fills and cancel one another via One-Cancels-Other (OCO) links, a standalone limit order enters the broker's active queue immediately upon submission and acceptance. Furthermore, unlike stop orders (bt.Order.Stop) which represent adverse triggers that convert into market orders upon breach (often incurring slippage penalties), limit orders define strict boundary prices where execution can only occur at the limit price or at a price more favorable to the trader.
flowchart TD
    Submit["Strategy calls self.buy(exectype=bt.Order.Limit, price=P_limit)"] --> BrokerQueue["Broker receives order\nStatus: Submitted -> Accepted"]
    BrokerQueue --> NextBar["Next Bar arrives with (Open, High, Low, Close)"]
    NextBar --> CheckExpire{"order.expire()?\nDate > valid?"}
    CheckExpire -- Yes --> Expired["Order Status: Expired\n(Execution Aborted)"]
    CheckExpire -- No --> CheckGap{"Open <= P_limit?\n(Opening Gap Down)"}
    CheckGap -- Yes --> FillOpen["Price Improvement Fill!\nExecPrice = Open"]
    CheckGap -- No --> CheckTouch{"Low <= P_limit?\n(Intrabar Touch)"}
    CheckTouch -- Yes --> FillLimit["Intrabar Fill\nExecPrice = P_limit"]
    CheckTouch -- No --> StaysPending["Unfilled (Near Miss)\nRemains Pending in Queue"]
Backtrader limit order matching engine semantics
Backtrader evaluates resting limit orders inside the broker's _try_exec_limit() method at the arrival of each new bar. Understanding the mathematical conditions for both buy and sell limit orders is essential for auditing historical fills.
1. Buy limit order execution rules
When a strategy submits a buy limit order with limit price P_limit:
Condition 1: Opening Gap Improvement
If Open <= P_limit:
    Execution Price = Open
    (Trader receives favorable execution below the limit price)

Condition 2: Intrabar Penetration or Touch
If Open > P_limit and Low <= P_limit:
    Execution Price = P_limit
    (Trader executes exactly at the requested limit price)

Condition 3: Unfilled Non-Execution
If Low > P_limit:
    Execution Price = None
    (Order remains in the pending queue or expires)
In Backtrader's default configuration, when a bar opens below your buy limit price (Open <= P_limit), the broker grants you price improvement: the order fills at Open rather than P_limit. If the bar opens above P_limit but the bar's Low dips to or below P_limit, Backtrader assumes the order was touched or penetrated intrabar, filling the order at exactly P_limit.
2. Sell limit order execution rules
For a sell limit order (either closing a long position or opening a short position) with limit price P_limit:
Condition 1: Opening Gap Improvement
If Open >= P_limit:
    Execution Price = Open
    (Trader receives favorable execution above the limit price)

Condition 2: Intrabar Penetration or Touch
If Open < P_limit and High >= P_limit:
    Execution Price = P_limit
    (Trader executes exactly at the requested limit price)

Condition 3: Unfilled Non-Execution
If High < P_limit:
    Execution Price = None
    (Order remains in the pending queue or expires)
When a stock gaps open above your sell limit price (Open >= P_limit), Backtrader executes your sale at Open, locking in the higher opening price. If the market opens below the limit but pushes upward during the bar so that High >= P_limit, the order executes at P_limit.
Order validity, lifecycles, and the expiration trap
Limit orders rarely remain active forever. In professional trading, unfilled limit orders are either modified, cancelled, or designated with specific time-in-force parameters. Backtrader models order expiration through the valid parameter in self.buy() or self.sell().
Order validity modes
Backtrader supports four distinct validity formats:
- Good-'Til-Cancelled (GTC): Set by default when
valid=Noneor omitted. The order persists in the broker's pending queue indefinitely across bars until filled, explicitly cancelled viaself.cancel(order), or rejected due to margin constraints. - Calendar Date (
datetime.date):valid=datetime.date(2026, 1, 8). The order remains active through all bars up to and including January 8, 2026. On the first bar dated strictly after January 8, the order transitions tobt.Order.Expired. - Exact Datetime (
datetime.datetime):valid=datetime.datetime(2026, 1, 8, 16, 0). Useful for intraday bars where an order should expire at a specific market close. - Relative Offset (
datetime.timedelta):valid=datetime.timedelta(days=1)or float bar offsets.
The daily bar expiration trap: valid=bt.Order.DAY
A frequent pitfall for algorithmic traders moving from live brokers (like Interactive Brokers) to Backtrader is the handling of valid=bt.Order.DAY.
In Backtrader's source code (bt.Order.__init__), bt.Order.DAY is defined as datetime.timedelta(), which is an empty delta (0 days). When passed to an order on a daily chart on bar T (e.g., 2026-01-05), Backtrader computes:
if self.valid == self.DAY:
    valid = datetime.datetime.combine(
        self.data.datetime.date(), datetime.time(23, 59, 59, 9999)
    )
self.valid = self.data.date2num(valid)
This assigns order.valid a timestamp of 2026-01-05 23:59:59. When the next daily bar arrives on 2026-01-06 00:00:00, the broker runs its pre-matching lifecycle check inside bbroker.py:
if order.expire():
    self.notify(order)
    self._ococheck(order)
    self._bracketize(order, cancel=True)
Inside order.expire():
if self.valid and self.data.datetime[0] > self.valid:
    self.status = Order.Expired
    self.executed.dt = self.data.datetime[0]
    return True
Because 2026-01-06 00:00:00 > 2026-01-05 23:59:59, the order is marked Expired immediately at the start of Bar 2, before the broker ever evaluates the bar's OHLC prices against the limit price! As a result, the order never has an opportunity to execute on the subsequent day.
[!WARNING] On daily bar backtests, do not pass
valid=bt.Order.DAYif you want the order to execute during the next trading day. Instead, passvalid=datetime.timedelta(days=1)or explicit future datesself.data.datetime.date(0) + datetime.timedelta(days=1).
Synthetic 5-bar audit: Reproducible test implementation
To rigorously verify Backtrader's limit order matching engine, we construct a 5-bar synthetic OHLC sequence designed with four distinct boundary conditions:
- Bar 1 (Day 1): Initial evaluation bar. Submit Order 1 (Buy Limit at 100.0, GTC).
- Bar 2 (Day 2): Opening Gap Down (
Open = 98.00 < 100.00). Verifies whether the broker grants opening price improvement (Fill = 98.00). Submit Order 2 (Buy Limit at 100.0, GTC). - Bar 3 (Day 3): Exact Price Touch (
Open = 101.00,Low = 100.00). Verifies whether an intrabar touch matching the limit price triggers a fill at100.00. Submit Order 3 (Buy Limit at 100.0, valid until Day 4). - Bar 4 (Day 4): Near Miss by 0.05 Ticks (
Open = 102.00,Low = 100.05 > 100.00). Verifies that the order remains unfilled and pending. - Bar 5 (Day 5): Validity Expiration (
Open = 103.00,Low = 101.00). Verifies that the broker transitions Order 3 tobt.Order.Expiredprior to matching.
Python audit script
The following script executes this test suite with explicit order lifecycle and bar-level event logging:
from datetime import date, datetime, timedelta
import backtrader as bt
import pandas as pd


class LimitAuditStrategy(bt.Strategy):
    """Audits Backtrader limit order execution across gaps, touches, misses, and expiry."""

    def __init__(self):
        self.order_map = {}

    def log(self, text: str):
        dt = self.datas[0].datetime.date(0)
        print(f"[{dt}] [Bar {len(self):02d}] {text}")

    def notify_order(self, order: bt.Order):
        ref = order.ref
        tag = self.order_map.get(ref, f"Order {ref}")
        status = order.getstatusname()

        if order.status == bt.Order.Completed:
            self.log(
                f"EVENT: {tag} COMPLETED | ExecPrice={order.executed.price:.2f} | "
                f"Limit={order.created.price:.2f} | Size={order.executed.size}"
            )
        elif order.status == bt.Order.Expired:
            self.log(f"EVENT: {tag} EXPIRED")
        elif order.status == bt.Order.Accepted:
            self.log(f"EVENT: {tag} ACCEPTED")
        elif order.status == bt.Order.Submitted:
            self.log(f"EVENT: {tag} SUBMITTED")

    def next(self):
        bar_idx = len(self)
        o = self.data.open[0]
        h = self.data.high[0]
        l = self.data.low[0]
        c = self.data.close[0]
        self.log(f"MARKET OHLC: O={o:.2f}, H={h:.2f}, L={l:.2f}, C={c:.2f}")

        if bar_idx == 1:
            # Test 1: Gap-down opening price improvement
            self.log("ACTION: Submit Order 1 (Buy Limit @ 100.0, GTC) -> Target Gap Fill")
            order = self.buy(exectype=bt.Order.Limit, price=100.0)
            self.order_map[order.ref] = "Order 1 [Gap Improvement]"

        elif bar_idx == 2:
            # Test 2: Exact touch execution
            self.log("ACTION: Submit Order 2 (Buy Limit @ 100.0, GTC) -> Target Exact Touch")
            order = self.buy(exectype=bt.Order.Limit, price=100.0)
            self.order_map[order.ref] = "Order 2 [Exact Touch]"

        elif bar_idx == 3:
            # Test 3 & 4: Near miss followed by date expiration
            validity_date = date(2026, 1, 8)
            self.log(f"ACTION: Submit Order 3 (Buy Limit @ 100.0, valid={validity_date}) -> Target Miss & Expiry")
            order = self.buy(exectype=bt.Order.Limit, price=100.0, valid=validity_date)
            self.order_map[order.ref] = "Order 3 [Near-Miss & Expiry]"


def run_limit_audit():
    dates = [datetime(2026, 1, 5) + timedelta(days=i) for i in range(5)]
    bars = [
        {"datetime": dates[0], "open": 105.00, "high": 106.00, "low": 102.00, "close": 103.00, "volume": 1000},
        {"datetime": dates[1], "open": 98.00, "high": 101.00, "low": 97.00, "close": 99.00, "volume": 1000},
        {"datetime": dates[2], "open": 101.00, "high": 102.00, "low": 100.00, "close": 101.50, "volume": 1000},
        {"datetime": dates[3], "open": 102.00, "high": 103.00, "low": 100.05, "close": 102.50, "volume": 1000},
        {"datetime": dates[4], "open": 103.00, "high": 104.00, "low": 101.00, "close": 102.00, "volume": 1000},
    ]

    dataframe = pd.DataFrame(bars).set_index("datetime")

    cerebro = bt.Cerebro()
    cerebro.broker.setcash(100000.0)
    cerebro.broker.setcommission(commission=0.0)

    data_feed = bt.feeds.PandasData(dataname=dataframe)
    cerebro.adddata(data_feed)
    cerebro.addstrategy(LimitAuditStrategy)

    print("=== STARTING BACKTRADER LIMIT ORDER AUDIT ===")
    cerebro.run()
    print("=== AUDIT RUN COMPLETED ===")


if __name__ == "__main__":
    run_limit_audit()
Execution log output
Executing the script yields the following chronological audit trace:
=== STARTING BACKTRADER LIMIT ORDER AUDIT ===
[2026-01-05] [Bar 01] MARKET OHLC: O=105.00, H=106.00, L=102.00, C=103.00
[2026-01-05] [Bar 01] ACTION: Submit Order 1 (Buy Limit @ 100.0, GTC) -> Target Gap Fill
[2026-01-06] [Bar 02] EVENT: Order 1 [Gap Improvement] (Ref 1) SUBMITTED
[2026-01-06] [Bar 02] EVENT: Order 1 [Gap Improvement] (Ref 1) ACCEPTED
[2026-01-06] [Bar 02] EVENT: Order 1 [Gap Improvement] (Ref 1) COMPLETED | ExecPrice=98.00 | Limit=100.00 | Size=1
[2026-01-06] [Bar 02] MARKET OHLC: O=98.00, H=101.00, L=97.00, C=99.00
[2026-01-06] [Bar 02] ACTION: Submit Order 2 (Buy Limit @ 100.0, GTC) -> Target Exact Touch
[2026-01-07] [Bar 03] EVENT: Order 2 [Exact Touch] (Ref 2) SUBMITTED
[2026-01-07] [Bar 03] EVENT: Order 2 [Exact Touch] (Ref 2) ACCEPTED
[2026-01-07] [Bar 03] EVENT: Order 2 [Exact Touch] (Ref 2) COMPLETED | ExecPrice=100.00 | Limit=100.00 | Size=1
[2026-01-07] [Bar 03] MARKET OHLC: O=101.00, H=102.00, L=100.00, C=101.50
[2026-01-07] [Bar 03] ACTION: Submit Order 3 (Buy Limit @ 100.0, valid=2026-01-08) -> Target Miss & Expiry
[2026-01-08] [Bar 04] EVENT: Order 3 [Near-Miss & Expiry] (Ref 3) SUBMITTED
[2026-01-08] [Bar 04] EVENT: Order 3 [Near-Miss & Expiry] (Ref 3) ACCEPTED
[2026-01-08] [Bar 04] MARKET OHLC: O=102.00, H=103.00, L=100.05, C=102.50
[2026-01-09] [Bar 05] EVENT: Order 3 [Near-Miss & Expiry] (Ref 3) EXPIRED
[2026-01-09] [Bar 05] MARKET OHLC: O=103.00, H=104.00, L=101.00, C=102.00
=== AUDIT RUN COMPLETED ===
Reconciliation audit table
We can reconcile the expected behavior against actual broker matching by aligning bar intervals, market quotes, order states, and execution prices:
| Bar # | Calendar Date | Bar OHLC Quotes | Order Under Test | Lifecycle Transition | Expected Fill | Actual Fill | Matching Rule Triggered |
|---|---|---|---|---|---|---|---|
| 01 | 2026-01-05 | O: 105.00, H: 106.00L: 102.00, C: 103.00 | Order 1 (Buy Limit @ 100.0, GTC) | Created in strategy next() | None (next-bar matching) | None | Order placed into pending submission queue. |
| 02 | 2026-01-06 | O: 98.00, H: 101.00L: 97.00, C: 99.00 | Order 1 Order 2 (Buy Limit @ 100.0, GTC) | Order 1: Accepted → Completed Order 2: Created in next() | Order 1: 98.00Order 2: None | Order 1: 98.00Order 2: None | Gap Price Improvement: Open <= P_limit (98.00 <= 100.00). Filled at Open. |
| 03 | 2026-01-07 | O: 101.00, H: 102.00L: 100.00, C: 101.50 | Order 2 Order 3 (Buy Limit @ 100.0, Valid: 2026-01-08) | Order 2: Accepted → Completed Order 3: Created in next() | Order 2: 100.00Order 3: None | Order 2: 100.00Order 3: None | Exact Intrabar Touch: Open > P_limit (101.00 > 100.00) and Low <= P_limit (100.00 <= 100.00). Filled at P_limit. |
| 04 | 2026-01-08 | O: 102.00, H: 103.00L: 100.05, C: 102.50 | Order 3 | Order 3: Accepted → Pending | None | None | Near-Miss Rejection: Low > P_limit (100.05 > 100.00). Missed by 0.05 ticks. Remains pending. |
| 05 | 2026-01-09 | O: 103.00, H: 104.00L: 101.00, C: 102.00 | Order 3 | Order 3: Pending → Expired | None | None | Date Expiration: Current bar date (2026-01-09) > validity (2026-01-08). Cancelled prior to matching. |
Key takeaways from the reconciliation
- Opening gaps yield real price improvement: In Bar 2, Backtrader filled the buy limit at
98.00, saving $2.00 per share relative to the requested100.00limit price. This correctly reflects real exchange mechanics, where a resting limit order catches an auction opening that clears lower. - Boundary touches execute at limit: In Bar 3, because the opening price was above the limit, the broker did not use the opening price. When
Lowtouched100.00, it executed at100.00. - Strict tick-level filtering prevents leaks: In Bar 4, despite coming within 5 cents of the limit, the order remained completely untouched. Backtrader does not simulate soft touches or fuzzy bounds.
- Order expiration precedes bar matching: In Bar 5, Order 3 expired during the pre-matching sweep. Even if Bar 5 had gapped down to
90.00, the order would not have executed because expiration is evaluated before order execution.
Intrabar touch ambiguity and the "phantom fill" problem
While Backtrader's matching engine follows clean mathematical logic, relying naively on limit order fills on coarse bar data (such as daily OHLC) introduces substantial simulation bias, often known as the phantom fill problem.
flowchart LR
    ExchangeBook["Live Exchange Order Book\n(Price-Time Priority Queue)"] --> QueueDepth["Queue: 50,000 shares ahead of you"]
    QueueDepth --> TradeTape["Tape: Low trades 500 shares at $100.00\nThen price rebounds to $101.00"]
    TradeTape --> LiveResult["Live Outcome: UNFILLED\n(Did not clear front of queue)"]

    DailyBar["Backtest Simulation\n(Daily OHLC Bar)"] --> BarCondition["Condition: Low <= 100.00 is TRUE"]
    BarCondition --> SimResult["Backtest Outcome: 100% FILLED at $100.00\n(Phantom Fill Distortion)"]
1. Queue priority and order book depth
In real equity and derivatives exchanges, orders are matched according to price-time priority. When price touches $100.00, your order is appended to the back of the queue at that price level. If 20,000 shares of buy limit interest are already resting at $100.00 and aggressive sellers dump only 2,000 shares before buying pressure drives the price back up, your order will not fill.
Yet, on a daily OHLC bar, that transaction registers as Low = 100.00. In Backtrader:
elif plimit >= plow:
    # Matches 100% of the requested size at limit price!
    self._execute(order, ago=0, price=p)
The simulator assumes 100% fill probability for any price touch, regardless of volume traded at that level or queue position. This leads quantitative researchers to develop strategies that appear wildly profitable in backtests (especially mean-reversion pullbacks) but fail completely in live forward execution.
2. Adverse selection and fill skew
In liquid markets, resting limit orders suffer from adverse selection:
- When prices quickly rebound away from your limit price after a light touch, you are unfilled (missing the winning trade).
- When prices crash heavily through your limit price on high volume (e.g., an earnings surprise or flash crash), your order is guaranteed to fill (capturing the severe losing trade).
Because a standard bar-level backtester fills 100% of both regimes, historical results are heavily biased upward.
Mitigating fill assumptions in Backtrader
To protect against phantom fills in Backtrader:
- Require price penetration (Conservative Buffer): Avoid submitting orders where
Low == P_limit. In strategy logic, assume a fill only if price clears through the limit by a defined tick buffer:Code P_limit = Target_Price - (1.5 * Tick_Size) - Apply Volume Fillers: Backtrader allows attaching a volume filler function to the broker via
cerebro.broker.set_filler(). This restricts the filled size of an order to a percentage of the bar's traded volume:Code def volume_percentage_filler(order, price, ago): bar_volume = order.data.volume[ago] max_fillable = bar_volume * 0.05 # Cap at 5% of bar volume return min(order.executed.remsize, max_fillable) cerebro.broker.set_filler(volume_percentage_filler) - Use Limit Slippage: Configure
cerebro.broker.set_slippage_perc()orslip_limit=Trueto introduce artificial penalty slippage on limit fills.
Comparing limit order execution across engines
Different backtesting platforms handle limit order modeling with varying degrees of realism and configurability. The table below outlines how Backtrader compares to standard industry alternatives:
| Execution Feature | Backtrader (bbroker) | Vectorbt / Vectorbt Pro | QuantConnect (LEAN Engine) | OpenBacktesting (0.2.1) |
|---|---|---|---|---|
| Execution Architecture | Event-driven bar-by-bar queue sweep | Vectorized matrix operations / Event loop | Event-driven tick, second, and minute pipeline | Pure Python deterministic bar-by-bar engine |
| Opening Gap Improvement | Supported (Open <= P_limit fills at Open) | Configurable via execution models | Supported via native exchange models | Supported with deterministic price resolution |
| Exact Touch Handling | Fills 100% at P_limit on Low <= P_limit | Fills at limit price if low crosses boundary | Evaluates quote/trade tick data & queue depth | Bar-level touch with configurable fill rules |
| Validity Modes | GTC, Date, Datetime, Timedelta (Order.DAY trap) | Bar index validity and expiry offsets | GTC, Day, GTD (Good-Til-Date), IOC, FOK | Explicit bar lifespan and GTC models |
| Adverse Selection Modeling | Optional volume filler (set_filler) | Volume cross matrix constraints | Native fill models with order book simulation | Inspectable order logs with volume thresholds |
| Order Inspection & Audit | In-memory via notify_order() callbacks | In-memory trade and order DataFrames | Cloud logs, SQL database, and local debugging | SQLite trial persistence & local Studio UI |
Single-asset limit modeling in OpenBacktesting
When developing systematic trading systems, opaque matching behavior and hidden order mutations are prime sources of research drift. OpenBacktesting (0.2.1) provides an independent, lightweight Python engine (>=3.12,<3.15) specifically architected for single-asset historical OHLCV bar-by-bar research.
Deterministic order lifecycles
In OpenBacktesting, the separation between signal generation and order execution is strictly enforced:
- Bar Close Signal Phase: Indicators, signals, and target allocations are calculated strictly on completed historical bars.
- Bar Open / Intrabar Matching Phase: Orders submitted at bar close are evaluated on the incoming bar using explicit, deterministic matching rules. There are no magical fills or silent state overwrites.
Complete SQLite trial persistence and inspection
Rather than relying on ephemeral console prints or debugging breakpoints across hundreds of lines of framework code, OpenBacktesting logs every order event directly into a structured SQLite database:
flowchart LR
    Strategy["Strategy Signal Generation"] --> OrderCreate["Order Created\n(Price, Size, Expiry)"]
    OrderCreate --> Matching["Deterministic Bar Matching Engine\n(Open Gaps, Boundary Bounds)"]
    Matching --> SQLite["SQLite Trial Storage\n(Orders, Fills, Equity Curve)"]
    SQLite --> StudioUI["OpenBacktesting Studio UI\n(Inspectable Trades & Bar Chart Alignment)"]
Every limit order lifecycle event—submission, acceptance, partial fills, full executions, price improvement adjustments, and cancellations—is permanently recorded. Researchers can inspect:
- The exact bar index and timestamp when the order was submitted.
- The market OHLC conditions at the time of execution.
- The difference between requested limit price and actual executed price.
- Slippage, commission impact, and remaining position size.
This inspectability guarantees that when a strategy exhibits alpha from limit order fills, the researcher can audit every single fill against historical price action in the local Studio UI before committing capital.
Limit order backtesting best practices checklist
Before putting any limit-order-based strategy into production, run through this verification checklist:
- Audit Opening Gap Assumptions: Confirm whether your backtesting engine grants opening price improvement (
Open < P_limit) and verify that your live broker provides similar auction price improvement. - Avoid the Daily Bar
Order.DAYTrap: In Backtrader daily bar scripts, do not usevalid=bt.Order.DAY. Usedatetime.timedelta(days=1)or explicit target calendar dates to avoid instant expiration. - Inspect Order Lifecycles via Callbacks: Implement a comprehensive
notify_order()method to print and verifySubmitted,Accepted,Completed, andExpiredstates for every order. - Stress Test Intrabar Touches: Test strategy sensitivity by adding a conservative buffer (e.g., 0.5 to 1.0 ATR or multiple ticks) to your limit prices. If strategy profitability collapses when exact touches do not fill, the edge is an artifact of the simulator.
- Enforce Volume Participation Limits: Attach a volume filler to cap order execution sizes at a modest percentage (e.g., 1% to 5%) of the bar's total traded volume.
- Differentiate Standalone Limits from Composite Brackets: Remember that standalone limit orders enter the broker queue immediately, whereas take-profit limit orders in bracket structures depend on parent order execution.
- Persist and Verify Every Trial: Use a reproducible, inspectable backtesting framework like OpenBacktesting to log all order states to SQLite and inspect executions visually on historical charts.