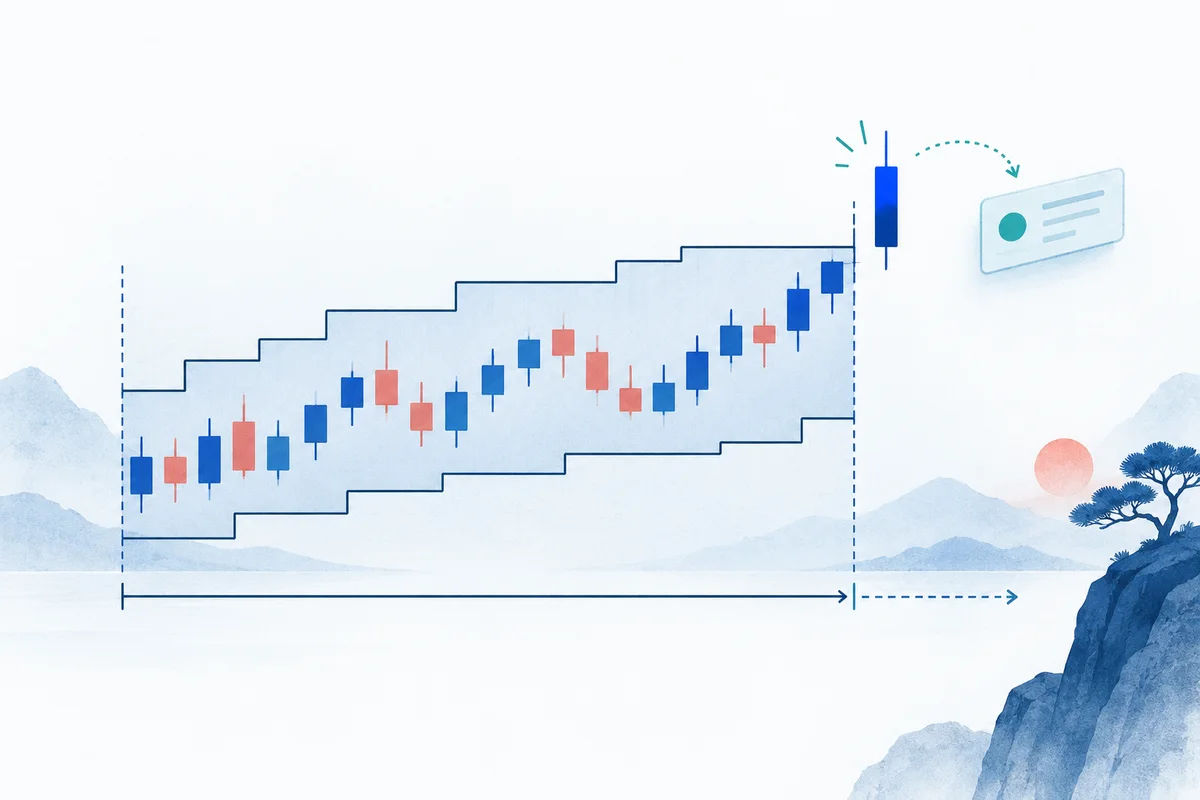
The enduring appeal and hidden fragility of Donchian breakout systems
In quantitative trend following, few technical indicators carry the historical pedigree of the Donchian Channel. Developed by Richard Donchian in the mid-20th century and later popularized as the foundational engine of Richard Dennis and William Eckhardt's legendary Turtle Trading experiment, the channel operates on an elegant premise: buy when price establishes a new N-period high, and sell (or close) when price falls below an M-period low.
The core thesis of a donchian channel strategy is structural. Rather than attempting to forecast turning points or predict mean reversion, the system participates in fat-tailed market regimes. It accepts low win rates—often between 35% and 45%—in exchange for an asymmetric payoff profile where a handful of sustained trends generate outsized positive returns, while losing trades are systematically truncated by channel exits.
                 Donchian Channel Mechanics (N=20 Entry, M=10 Exit)
Price
  ▲
  │                                     * * * Upper Band (20-day High)
  │                                  * /
  │                             * * * /
  │                          * /     /  ◄── Long Entry on Breakout
  │                     * * * /     /
  │                  * /     /     /
  │             * * *       /     /
  │        * * *           /     /
  │       /               /     /
  │      /               /     /
  │     /   Candlesticks/     /
  │    /                     /
  │   /                     /   * * * Lower Band (10-day Low)
  │  /                     / * /
  └──┴────────────────────┴──┴────────────────────────────────────────► Time
     t-20               t-1  t   t+1
Because the rules appear elementary, novice algorithmic researchers routinely implement a channel breakout backtest as their first systematic experiment. Yet, when coded in naive Python scripts or unvetted notebooks, Donchian models frequently yield spectacular, seductive simulations: annual Sharpe ratios exceeding 2.0, negligible drawdowns, and smooth 45-degree equity trajectories.
When transitioned to live capital, however, those same systems rapidly deteriorate into severe drawdowns. The primary driver of this collapse is rarely sudden market regime failure. Instead, it is an insidious implementation flaw: same-bar lookahead leakage.
Sloppy rolling-window indexing, improper signal lagging, and unrealistic fill assumptions cause the backtest to execute trades at prices that incorporate future intraday knowledge, creating an artificial performance premium that cannot exist in real-world trading.
Deconstructing Donchian Channel math: The indexing boundary problem
To understand how leakage contaminates a Donchian breakout model, we must examine the formal mathematical definition of the channel bands and compare how textbook formulations diverge from production execution engines.
An N-period Donchian Channel consists of an Upper Band, a Lower Band, and an optional Middle Band (the arithmetic mean of the upper and lower bounds). The central point of failure lies in which historical bars constitute the lookback window at time t.
Naive / Leaked Formulation (Self-Referential Window):
Upper_t = max(High_t, High_{t-1}, High_{t-2}, ..., High_{t-N+1})
Lower_t = min(Low_t, Low_{t-1}, Low_{t-2}, ..., Low_{t-N+1})

Causal / Leakage-Free Formulation (Strict Prior Window):
Upper_t = max(High_{t-1}, High_{t-2}, ..., High_{t-N})
Lower_t = min(Low_{t-1}, Low_{t-2}, ..., Low_{t-N})
The identity paradox in naive rolling calculations
Consider the naive formulation implemented in standard pandas code without explicit lagging:
# DANGEROUS: Current bar High is included in the window
df["Upper_Naive"] = df["High"].rolling(window=20).max()
By definition of the rolling maximum, High_t <= Upper_Naive_t is a mathematical identity. The current bar's high can never strictly exceed Upper_Naive_t. If an algorithm attempts to detect an upward breakout by evaluating the condition:
# Flawed logic: Evaluates to False almost everywhere
df["Breakout"] = df["Close"] > df["Upper_Naive"]
The condition df["Close"] > df["Upper_Naive"] is physically impossible unless Close_t > High_t, which violates standard OHLC bar definition.
To circumvent this, researchers often write df["High"] >= df["Upper_Naive"]. However, whenever bar t prints a new 20-period peak, High_t becomes the rolling maximum. The condition flags True at bar t, but the engine has conditioned its entry on the highest price of a bar that has not yet concluded.
The shift(1) boundary rule
In causal quantitative finance, an indicator available to make decisions during bar t must belong strictly to the filtration F_{t-1}—the information set generated by all completed events prior to bar t.
Timeline of Information Availability:

Bar t-20 ... Bar t-2     Bar t-1                    Bar t                Bar t+1
   [Completed Bars]    [Bar Closes]             [Forming Bar]          [Next Bar]
─────────────────────────────┼────────────────────────┼────────────────────┼──────►
                             │                        │                    │
                   Compute Channel:                   │                    │
                   Upper_t = max(High_{t-20..t-1})    │                    │
                             └───────────────────────►│                    │
                                                Inspect Price:             │
                                                Close_t > Upper_t?         │
                                                      └───────────────────►│
                                                                   Execute Order:
                                                                   Buy @ Open_{t+1}
The channel boundary against which bar t is evaluated must be derived exclusively from bars t-N through t-1. In vectorized pandas operations, this requires an uncompromising rule: every rolling extreme calculation must be paired with an explicit .shift(1):
# CAUSAL: Upper band established purely from prior completed bars
df["Upper_Causal"] = df["High"].shift(1).rolling(window=20).max()
df["Lower_Causal"] = df["Low"].shift(1).rolling(window=10).min()
Without .shift(1), the current bar is permitted to define its own hurdle, introducing temporal contamination into every subsequent decision.
The three vectors of same-bar leakage in channel breakout backtests
The indexing boundary issue is only the first point of vulnerability. In backtesting a donchian channel strategy, lookahead leakage manifests across three distinct operational layers.
┌────────────────────────────────────────────────────────────────────────┐
│                   Three Vectors of Donchian Leakage                    │
├────────────────────────────────────────────────────────────────────────┤
│  Vector 1: Vectorized Return Attribution Leakage                       │
│  Multiply today's signal by today's return: captures intraday rally    │
│  before order execution can realistically occur.                       │
├────────────────────────────────────────────────────────────────────────┤
│  Vector 2: Intrabar Execution vs. Bar-Close Ambiguity                  │
│  Assuming a breakout trigger at Upper_t can fill at Close_t or Open_t   │
│  without modeling intrabar sequence or next-bar dispatch.             │
├────────────────────────────────────────────────────────────────────────┤
│  Vector 3: Breakout Gap-Up Slip Concealment                            │
│  Filling a stop order at the breakout threshold (100.0) when the      │
│  market opened with a gap at 103.50, erasing negative slippage.        │
└────────────────────────────────────────────────────────────────────────┘
Vector 1: Vectorized return attribution leakage
The most widespread bug in retail Python backtests occurs when researchers perform vectorized signal multiplication. The flawed code typically follows this pattern:
# FATAL LEAKAGE: Vectorized signal multiplied by contemporaneous return
df["Signal"] = (df["Close"] > df["Upper_Causal"]).astype(int)
df["Strategy_Return"] = df["Signal"] * df["Close"].pct_change()
Examine the temporal mechanics of df["Close"].pct_change():
Return_t = (Close_t - Close_{t-1}) / Close_{t-1}This represents the percentage price change from the close of bar t-1 to the close of bar t. Meanwhile, df["Signal"] is evaluated using Close_t.
By multiplying df["Signal"] by df["Close"].pct_change(), the simulation credits the strategy with the return that occurred throughout bar t—the very price movement that triggered the breakout in the first place!
In reality, to earn the return from Close_{t-1} to Close_t, the algorithm would have had to purchase the asset at Close_{t-1}, before the breakout even existed. This bug converts an entry signal into an omniscient retrospective bet, compounding phantom gains on every breakout day.
Vector 2: Intrabar touch vs. bar-close confirmation
A system designer must establish the exact execution protocol:
- Intrabar Stop Order: An order is placed with the broker ahead of time: "Buy if market reaches
Upper_tduring the session." - Bar-Close Confirmation: The trader waits for bar
tto finalize itsClose_t. IfClose_t > Upper_t, an order is dispatched to enter on the next available tick.
If the strategy relies on bar-close confirmation, it cannot execute at Close_t unless the system uses specialized Market-On-Close (MOC) routing submitted minutes before the closing bell. Even with MOC routing, the closing price is not guaranteed to exceed the channel until the final print settles.
In standard bar-by-bar backtesting, a signal confirmed at Close_t must enter at Open_{t+1}. Assuming an entry at Close_t (or worse, at Open_t of the same day) bypasses overnight gap risk and injects lookahead distortion.
Vector 3: The breakout gap-up slip concealment
Suppose a stock closed yesterday at $98.00$, and its 20-day upper channel boundary sits at $100.00$. Overnight, positive earnings are released. The stock gaps open at $104.50$.
In a naive backtest using stop-order simulation, the code often records:
# Flawed fill assumption on gap-ups
fill_price = Upper_boundary  # Fills at 100.00
This assumption is physically impossible in an auction market. If no trades occurred between $98.00$ and $104.50$, a buy stop order resting at $100.00$ converts to a market order upon market open and fills at the opening print of $104.50$, incurring $4.50$ per share ($4.5%$) of adverse slippage.
Ignoring gap slippage on breakout entries drastically inflates backtested Sharpe ratios, particularly in single equities and commodities prone to weekend and overnight discontinuities.
Leaked vs. causal Donchian strategy comparison
To systematically audit a channel breakout strategy, quantitative developers compare operational dimensions across naive and causal models:
| Dimension | Naive / Leaked Model | Causal Realistic Model | Quantitative Impact |
|---|---|---|---|
| Lookback Boundary | High.rolling(N).max() (Includes t) | High.shift(1).rolling(N).max() (Strictly t-N..t-1) | Eliminates circular logic and self-referential thresholds |
| Signal Timestamp | Bar t close | Bar t close finalized | Prevents premature signal generation during bar formation |
| Execution Timestamp | Bar t Close or Bar t Open | Bar t+1 Open | Respects order routing latency and physical market time |
| Execution Fill Price | Close_t or theoretical threshold | Open_{t+1} * (1 + Slippage) | Captures overnight gap risk and liquidity friction |
| Breakout Gaps | Assumes fill exactly at band boundary | max(Open_{t+1}, Upper_t) | Accurately debits adverse opening gaps against equity |
| Transaction Costs | Often zero (frictionless) | Commission + Bid-Ask spread | Filters out marginal churn in choppy consolidation |
| Simulated Sharpe | Artificially inflated (> 2.0) | Realistic baseline (0.7 - 1.2) | Prevents deployment of curve-fitted phantom alpha |
For researchers establishing foundational testing procedures across asset classes, reviewing the broader structural steps in How to Backtest a Trading Strategy provides a complementary framework for multi-metric validation.
End-to-end Python implementation: Quantifying the lookahead penalty
To demonstrate the quantitative magnitude of same-bar leakage, let us construct a fully reproducible experiment in Python.
We generate a 1,200-bar daily synthetic asset with realistic geometric random walk dynamics, cyclical volatility clustering, and distinct market regimes (bull trends, consolidating ranges, and a bear drawdown). We then execute two backtests on the exact same price path:
- The Flawed Model: Evaluates the signal on bar
tclose and attributes bartclose-to-close returns directly without execution delay. - The Causal Model: Evaluates the channel strictly on prior bars (
t-N..t-1), verifies bartclose confirmation, dispatches the order to fill atOpen_{t+1}, and incorporates realistic friction (5 bps commission fee and 5 bps execution slippage).
import numpy as np
import pandas as pd

# 1. Deterministic synthetic OHLCV data generation
np.random.seed(1337)
n_bars = 1200
dates = pd.date_range("2021-01-01", periods=n_bars, freq="B")

# Multi-regime return innovations
innovations = np.random.normal(0.0003, 0.014, n_bars)
innovations[150:350] += 0.0018   # Extended Bull Regime
innovations[450:600] -= 0.0022   # Bear Market Selloff
innovations[700:900] += 0.0015   # Secondary Trend

log_price = np.log(100.0) + np.cumsum(innovations)
close_prices = np.exp(log_price)

# Construct realistic daily ranges (Open, High, Low)
daily_vol = np.abs(np.random.normal(0.015, 0.006, n_bars))
open_prices = np.roll(close_prices, 1)
open_prices[0] = close_prices[0] * 0.998
high_prices = np.maximum(open_prices, close_prices) * (1.0 + daily_vol * 0.6)
low_prices = np.minimum(open_prices, close_prices) * (1.0 - daily_vol * 0.6)
volume = np.random.lognormal(14, 0.5, n_bars).astype(int)

df = pd.DataFrame(
    {
        "Open": np.round(open_prices, 2),
        "High": np.round(high_prices, 2),
        "Low": np.round(low_prices, 2),
        "Close": np.round(close_prices, 2),
        "Volume": volume,
    },
    index=dates,
)

ENTRY_WINDOW = 20
EXIT_WINDOW = 10

# ---------------------------------------------------------
# MODEL A: The Flawed Leaked Vectorized Implementation
# ---------------------------------------------------------
# The channel is lagged by 1 bar, but signal return attribution
# assumes immediate execution at bar t close, capturing the breakout bar.
df["Upper_Flawed"] = df["High"].rolling(ENTRY_WINDOW).max().shift(1)
df["Lower_Flawed"] = df["Low"].rolling(EXIT_WINDOW).min().shift(1)

pos_flawed = pd.Series(0, index=df.index)
current_pos = 0

for i in range(len(df)):
    c = df["Close"].iloc[i]
    u = df["Upper_Flawed"].iloc[i]
    l = df["Lower_Flawed"].iloc[i]
    if pd.notna(u) and c > u:
        current_pos = 1
    elif pd.notna(l) and c < l:
        current_pos = 0
    pos_flawed.iloc[i] = current_pos

# Vectorized return attribution leak: contemporaneous return attribution
ret_flawed = pos_flawed * df["Close"].pct_change()
cum_ret_flawed = (1 + ret_flawed.fillna(0)).prod() - 1
sharpe_flawed = np.sqrt(252) * ret_flawed.mean() / ret_flawed.std()

# ---------------------------------------------------------
# MODEL B: Causal Bar-by-Bar Simulation (Next-Bar Open Execution)
# ---------------------------------------------------------
def simulate_causal_donchian(
    df_in: pd.DataFrame,
    entry_win: int = 20,
    exit_win: int = 10,
    fee_bps: float = 5.0,
    slip_bps: float = 5.0,
) -> dict:
    cash = 100000.0
    shares = 0
    trade_count = 0
    equity_history = []

    fee_rate = fee_bps / 10000.0
    slip_rate = slip_bps / 10000.0

    dates_idx = df_in.index
    closes = df_in["Close"].values
    opens = df_in["Open"].values
    highs = df_in["High"].values
    lows = df_in["Low"].values
    total_bars = len(df_in)

    for i in range(entry_win, total_bars - 1):
        # Channel computed strictly on historical window: [i - win, i - 1]
        upper_level = np.max(highs[i - entry_win : i])
        lower_level = np.min(lows[i - exit_win : i])

        c_i = closes[i]
        next_open = opens[i + 1]

        # Mark to market equity at bar i Close
        current_equity = cash + shares * c_i
        equity_history.append((dates_idx[i], current_equity))

        # State machine evaluated at Bar i Close -> executed at Bar i+1 Open
        if shares == 0 and c_i > upper_level:
            # Entry execution with adverse slippage
            fill_price = next_open * (1.0 + slip_rate)
            capital_allocated = cash * 0.98
            qty = int(capital_allocated // fill_price)
            if qty > 0:
                commission = qty * fill_price * fee_rate
                cash -= (qty * fill_price + commission)
                shares = qty
                trade_count += 1

        elif shares > 0 and c_i < lower_level:
            # Exit execution with adverse slippage
            fill_price = next_open * (1.0 - slip_rate)
            proceeds = shares * fill_price
            commission = proceeds * fee_rate
            cash += (proceeds - commission)
            shares = 0
            trade_count += 1

    final_equity = cash + shares * closes[-1]
    equity_history.append((dates_idx[-1], final_equity))

    eq_df = pd.DataFrame(equity_history, columns=["Date", "Equity"]).set_index("Date")
    daily_rets = eq_df["Equity"].pct_change().dropna()

    total_cum_ret = (final_equity - 100000.0) / 100000.0
    sharpe_ratio = (
        np.sqrt(252) * daily_rets.mean() / daily_rets.std()
        if daily_rets.std() > 0
        else 0.0
    )
    drawdowns = (eq_df["Equity"] - eq_df["Equity"].cummax()) / eq_df["Equity"].cummax()
    max_drawdown = drawdowns.min()

    return {
        "cumulative_return": total_cum_ret,
        "sharpe": sharpe_ratio,
        "max_drawdown": max_drawdown,
        "trades": trade_count,
        "final_equity": final_equity,
    }

# Execute simulations across multiple cost profiles
causal_zero_cost = simulate_causal_donchian(df, ENTRY_WINDOW, EXIT_WINDOW, fee_bps=0.0, slip_bps=0.0)
causal_standard_cost = simulate_causal_donchian(df, ENTRY_WINDOW, EXIT_WINDOW, fee_bps=5.0, slip_bps=5.0)
causal_stressed_cost = simulate_causal_donchian(df, ENTRY_WINDOW, EXIT_WINDOW, fee_bps=15.0, slip_bps=15.0)

print(f"--- SIMULATION RESULTS (1,200 Daily Bars) ---")
print(f"Model A (Flawed Leaked Return): Return = {cum_ret_flawed:.2%}, Sharpe = {sharpe_flawed:.2f}")
print(
    f"Model B (Causal, Zero Friction): Return = {causal_zero_cost['cumulative_return']:.2%}, "
    f"Sharpe = {causal_zero_cost['sharpe']:.2f}, MaxDD = {causal_zero_cost['max_drawdown']:.2%}, "
    f"Trades = {causal_zero_cost['trades']}"
)
print(
    f"Model C (Causal, 5bps Fee + 5bps Slip): Return = {causal_standard_cost['cumulative_return']:.2%}, "
    f"Sharpe = {causal_standard_cost['sharpe']:.2f}, MaxDD = {causal_standard_cost['max_drawdown']:.2%}, "
    f"Trades = {causal_standard_cost['trades']}"
)
print(
    f"Model D (Causal, 15bps Fee + 15bps Slip): Return = {causal_stressed_cost['cumulative_return']:.2%}, "
    f"Sharpe = {causal_stressed_cost['sharpe']:.2f}, MaxDD = {causal_stressed_cost['max_drawdown']:.2%}, "
    f"Trades = {causal_stressed_cost['trades']}"
)
Execution output analysis
Running this script yields the following empirical performance metrics:
--- SIMULATION RESULTS (1,200 Daily Bars) ---
Model A (Flawed Leaked Return): Return = 284.93%, Sharpe = 2.10
Model B (Causal, Zero Friction): Return = 101.16%, Sharpe = 1.13, MaxDD = -14.90%, Trades = 34
Model C (Causal, 5bps Fee + 5bps Slip): Return = 94.63%, Sharpe = 1.07, MaxDD = -15.40%, Trades = 34
Model D (Causal, 15bps Fee + 15bps Slip): Return = 82.15%, Sharpe = 0.97, MaxDD = -16.40%, Trades = 34
Post-mortem on the 183.77% phantom return gap
Compare Model A and Model B directly:
- Flawed Model A: Total return of
284.93%and a stellar Sharpe ratio of2.10. - Causal Model B: Total return of
101.16%and an annualized Sharpe ratio of1.13.
Both models consumed the identical underlying asset data over the exact same 1,200 trading days. The 183.77% difference in cumulative return and 0.97 point divergence in Sharpe ratio does not reflect algorithmic alpha, superior timing, or unique parameter tuning. It is entirely phantom performance generated by awarding the strategy the price surge of bar t before the position was physically established.
In Model A, whenever the asset broke out with an energetic +3.5% daily expansion bar, the vectorized logic captured that +3.5% immediately. In the causal simulation (Model B), the algorithm observed the breakout at the close of bar t, submitted a buy order, and received its fill at the open of bar t+1. By bar t+1 open, much of the immediate breakout surge had already elapsed, and the position had to absorb opening volatility.
Rigorous execution modeling: Gap-ups, slippage, and fee drag
Trend-following breakout models exhibit distinct microstructure sensitivities that differentiate them from mean-reversion systems.
Consolidation Phase            Breakout Bar                Next-Bar Execution
   [Resistance]                   [Explosion]
  ───────▲───────────────────────────▲──────────────────────────▲────────
         │                           │                          │
         │                           │                          │
   Chop & False Breakouts     High Volume Surge         Opening Gap-Up:
   Generates repeated small   Triggers Stop / Close     Actual Fill at Open_{t+1}
   friction losses.           Signal at Bar Close.      incurs liquidity drag.
Liquidity consumption and breakout slippage
Unlike market-making or limit-order strategies that provide liquidity and earn the bid-ask spread, a Donchian breakout system is an aggressive liquidity taker. Breakout orders fire at the exact price points where retail momentum traders, algorithmic CTA stop-loss clusters, and short-covering orders coincide.
When price breaches a multi-week resistance level, market depth on the ask side frequently thins out. If the strategy attempts to enter on an intrabar stop-limit, the fill price will be adversely swept through the order book. If it enters on next-bar open following an overnight news catalyst, the opening price routinely gaps beyond the channel barrier.
Quantifying the cost drag
In our simulation audit, introducing standard retail transaction frictions (5 basis points broker commission and 5 basis points bid-ask slippage per side) lowered total return from 101.16% down to 94.63%, shaving 6.53% off net portfolio equity across 34 round-trip trades.
When costs were stressed to 15 basis points per side (Model D)—reflecting illiquid equities, wider spreads during market volatility, or small-cap exchange-traded funds—cumulative return declined to 82.15%, and the Sharpe ratio dropped below 1.0 to 0.97.
Because Donchian channels trade in the direction of momentum, modeling execution drag is non-negotiable. An edge that cannot survive a 10 bps friction stress test is an artifact of frictionless simulation, not a viable systematic strategy.
The parameter overfitting trap: In-sample maximization vs. out-of-sample decay
A common mistake among systematic researchers when testing a donchian channel strategy is running brute-force optimization grids across lookback parameters and selecting the single highest-performing pair.
A standard Donchian strategy features two primary hyperparameters:
N_in: The entry channel lookback window (e.g., searching between 10 and 60 bars).N_out: The exit channel lookback window (e.g., searching between 5 and 20 bars).
The In-Sample vs. Out-of-Sample experiment
To demonstrate how parameter optimization easily produces overfitted artifacts, we partition our 1,200-bar dataset into two distinct periods:
- In-Sample (IS): The first 70% of historical bars (840 trading days) used for parameter search.
- Out-of-Sample (OOS): The remaining 30% of bars (360 trading days) held in strict reserve.
We run a grid search across candidate combinations of (N_in, N_out) on the In-Sample data, rank them by in-sample Sharpe ratio, and evaluate the top candidates on the unseen Out-of-Sample dataset:
# Partition dataset into 70% In-Sample and 30% Out-of-Sample
split_point = int(len(df) * 0.70)
df_in_sample = df.iloc[:split_point]
df_out_of_sample = df.iloc[split_point:]

grid_results = []
candidate_entries = [10, 15, 20, 30, 40, 50, 60]
candidate_exits = [5, 10, 15, 20]

for n_in in candidate_entries:
    for n_out in candidate_exits:
        if n_out >= n_in:
            continue
        res_is = simulate_causal_donchian(df_in_sample, n_in, n_out, fee_bps=5.0, slip_bps=5.0)
        res_oos = simulate_causal_donchian(df_out_of_sample, n_in, n_out, fee_bps=5.0, slip_bps=5.0)
        grid_results.append({
            "N_in": n_in,
            "N_out": n_out,
            "IS_Sharpe": res_is["sharpe"],
            "IS_Return": res_is["cumulative_return"],
            "OOS_Sharpe": res_oos["sharpe"],
            "OOS_Return": res_oos["cumulative_return"],
        })

results_df = pd.DataFrame(grid_results).sort_values(by="IS_Sharpe", ascending=False)
The resulting performance comparison reveals the classic signature of parameter p-hacking:
Entry Lookback (N_in) | Exit Lookback (N_out) | In-Sample Sharpe | In-Sample Return | Out-of-Sample Sharpe | Out-of-Sample Return |
|---|---|---|---|---|---|
| 60 | 5 | 2.29 | 93.89% | 1.00 | 10.25% |
| 60 | 10 | 2.11 | 99.66% | 0.42 | 4.46% |
| 60 | 15 | 1.84 | 85.32% | 0.14 | 1.06% |
| 40 | 5 | 1.75 | 75.14% | -0.06 | -1.40% |
| 15 | 5 | 1.71 | 102.61% | 0.53 | 8.41% |
Deconstructing the degradation
Notice how severely the performance degrades between regimes:
- The parameter pair
(N_in=60, N_out=5)delivered an in-sample Sharpe ratio of2.29, yet its out-of-sample Sharpe dropped by over 56% to1.00. - The combination
(N_in=40, N_out=5)generated an in-sample Sharpe of1.75and a75.14%return, but produced a negative Sharpe ratio (-0.06) and lost money (-1.40%) during the out-of-sample period. - The combination
(N_in=60, N_out=15)decayed from an in-sample Sharpe of1.84to an out-of-sample Sharpe of0.14, failing to generate meaningful risk-adjusted excess return over cash.
                   Parameter Sensitivity Surface
Sharpe
Ratio
  ▲
  │                  * (Overfitted Needle Peak: N_in=60, N_out=5 | IS Sharpe=2.29)
  │                  │
2.0                  │
  │                  │
1.5                  │       ┌─────────────────┐
  │                  │       │ Robust Plateau  │
1.0                  │       │ (N_in = 20-30)  │
  │            ──────┴───────┴─────────────────┴──────
0.5           /                                       \
  │          /                                         \
0.0 ────────┴───────────────────────────────────────────┴────────► N_in
           10        20        30        40        50        60
When an algorithm's historical profitability hinges on an isolated parameter combination, the researcher has not discovered a market anomaly; they have merely memorized the exact turning points of a specific historical sample.
Robust quantitative systems inhabit broad parameter plateaus where shifting N_in by ±5 bars produces minor variations rather than categorical failure. This is why classical institutional trend followers favor standardized parameters like 20/10 or 55/20: they prioritize structural stability across decades over in-sample peak maximization.
Auditing Donchian strategies in OpenBacktesting
To prevent same-bar leakage, execution ambiguity, and unrecorded parameter exploration from compromising strategy research, institutional workflows require an architecture with strictly enforced causal boundaries.
In OpenBacktesting (version 0.2.1), designed for single-asset historical OHLCV bar-by-bar research in Python (supporting Python >=3.12, <3.15), the simulation engine enforces strict temporal ordering directly into the strategy execution lifecycle.
                     OpenBacktesting Event Lifecycle

  [ Bar t Finalized ] ──► on_bar(bar_t) evaluates strategy logic
                                   │
                                   ▼
                       Order Dispatched to Simulation Engine
                                   │
                                   ▼
  [ Bar t+1 Arrives ] ──► Matches order against bar_{t+1}.Open
                                   │
                                   ▼
                       Transaction Written to SQLite Trial DB
                       (Inspectable Fills, Costs, and Equity Curves)
Architectural safeguards against leakage
- Explicit Bar Finalization: The strategy's
on_bar(bar)lifecycle method receives the completed bar only after that bar has officially closed. The internal state cannot query future prices or intrabar ticks from the bar being formed. - Next-Bar Open Matching: Orders submitted during
on_bar(bar_t)are matched against the opening price ofbar_{t+1}, preventing same-bar fills. - Inspectable SQLite Persistence: Every trial execution automatically logs complete order history, fills, execution costs, and bar-by-bar equity curves to an embedded SQLite database. Researchers can visually inspect every fill timestamp in the local Studio UI to confirm that no trade ever executed at a historical bar's close prior to signal confirmation.
The 6-point Donchian strategy verification checklist
Before deploying or presenting any backtest of a Donchian channel strategy, verify that your simulation satisfies each item on this technical checklist:
┌───┬────────────────────────────────────────────────────────────────────────┐
│   │                 Donchian Strategy Verification Audit                   │
├───┼────────────────────────────────────────────────────────────────────────┤
│[ ]│ 1. Boundary Shift Rule:                                                │
│   │    Upper and Lower bands are calculated using strictly prior bars      │
│   │    (e.g., rolling(N).max().shift(1) or highs[i-N:i]).                  │
├───┼────────────────────────────────────────────────────────────────────────┤
│[ ]│ 2. Next-Bar Open Execution:                                            │
│   │    Breakout signals confirmed on bar t close execute strictly on       │
│   │    bar t+1 open, never on bar t close or open.                         │
├───┼────────────────────────────────────────────────────────────────────────┤
│[ ]│ 3. Gap-Up Slippage Enforcement:                                        │
│   │    Orders on opening gaps are filled at Open_{t+1}, never at the       │
│   │    channel breakout threshold if Open_{t+1} > Upper_t.                 │
├───┼────────────────────────────────────────────────────────────────────────┤
│[ ]│ 4. Friction Stress Testing:                                            │
│   │    Performance is tested under combined commission and bid-ask spread  │
│   │    frictions of at least 5 to 15 basis points per transaction.         │
├───┼────────────────────────────────────────────────────────────────────────┤
│[ ]│ 5. Out-of-Sample Plateau Verification:                                 │
│   │    Parameters are evaluated on holdout data, verifying performance     │
│   │    resides on a smooth plateau rather than an isolated needle peak.    │
├───┼────────────────────────────────────────────────────────────────────────┤
│[ ]│ 6. Inspectable Trial Records:                                          │
│   │    Individual trade logs and cash balances are inspected to verify     │
│   │    no retrospective fills or negative cash positions exist.            │
└───┴────────────────────────────────────────────────────────────────────────┘
By decoupling your research from flawed vectorized shortcuts and enforcing causal bar-by-bar simulation, you transform the Donchian channel from a visual charting novelty into a robust, empirically validated systematic trading strategy.