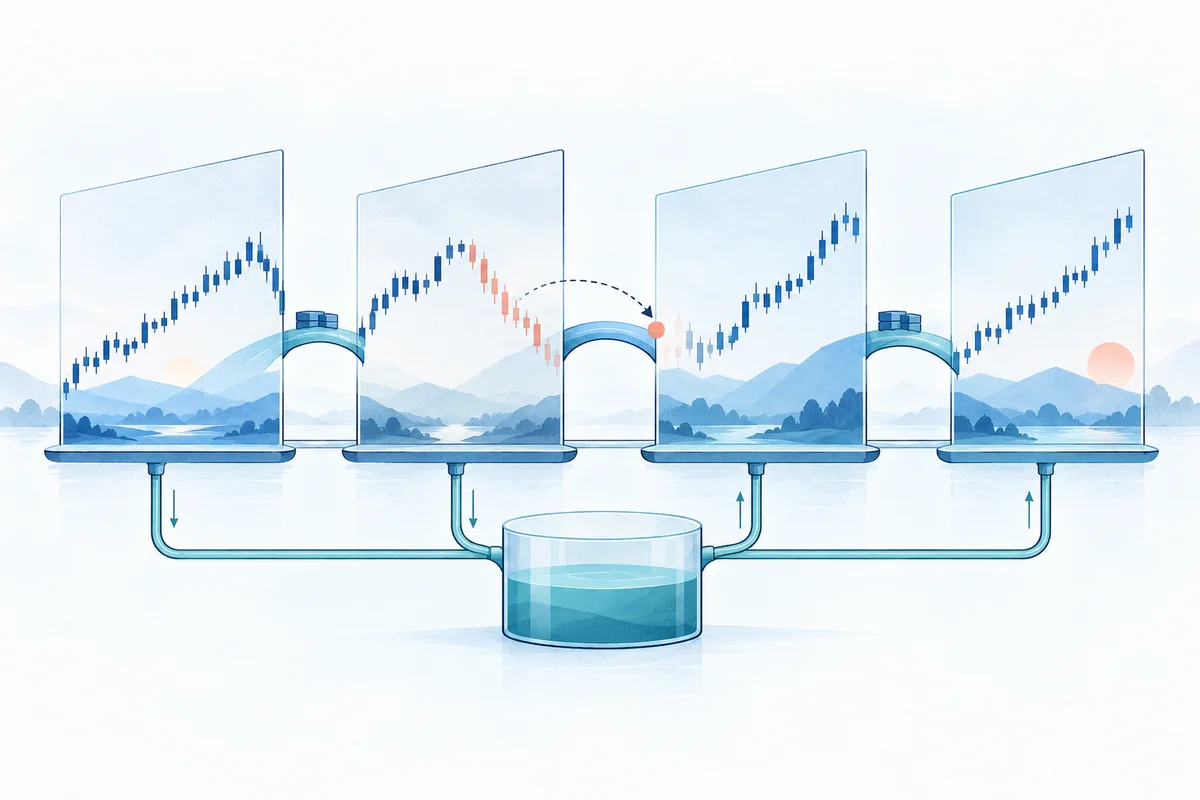
The structural complexity of futures vs. spot equities
Quantitative researchers transitioning from spot equities to futures markets encounter an entirely different market microstructure. In equity trading, common stock represents perpetual fractional equity in a corporation. Unless the company goes bankrupt, is acquired, or is delisted, the shares persist indefinitely, trade at their face dollar price, and require full cash funding (or standard 2:1 Reg-T margin).
Futures contracts, by contrast, are legally binding standardized derivative agreements traded on centralized exchanges—such as the Chicago Mercantile Exchange (CME), Intercontinental Exchange (ICE), and Eurex—to buy or sell a specified quantity of an underlying commodity, bond, or financial index at a predetermined price on a designated future date.
Spot Equities:    [ AAPL Perpetual Shares ] ───> Hold indefinitely (Cash PnL = Shares × ΔP)

Futures Series:   [ ES Sep24 (ESU24) ] ──> Roll ──> [ ES Dec24 (ESZ24) ] ──> Roll ──> [ ES Mar25 (ESH25) ]
                  └─ Expiration & Delivery ┘        └─ Term Structure (Contango / Backwardation) ┘
                  Cash PnL = Contracts × ΔP × Point Multiplier ($50/pt)
                  Collateral = Performance Bond (Initial & Maintenance Margin)
Backtesting futures requires accounting for four structural realities:
- Finite lifespans and expiration schedules: Every futures contract has an immutable expiration date. Traders cannot hold an individual contract indefinitely; they must close or roll the position before First Notice Day (FND) or Last Trading Day (LTD) to avoid cash settlement finality or physical commodity delivery.
- Point multipliers: Futures prices are quoted in index points, cents, or barrels, not total dollar value. An E-mini S&P 500 contract quoted at
5,400.00does not cost5,400; it controls$50 \times 5,400 = $270,000$ in notional market exposure. - Margin leverage and performance bonds: Futures do not involve borrowing money on interest in the traditional cash-equity sense. Instead, market participants post a refundable performance bond—Initial Margin (typically 3% to 12% of total notional value)—and must maintain a minimum Maintenance Margin balance.
- Daily mark-to-market (MtM) cash variation settlement: Every trading day at the close of the pit/electronic session, the clearinghouse calculates the settlement price. Unrealized gains are credited as cash, and unrealized losses are debited from the trader's account.
Failing to incorporate these mechanics into historical backtesting engines produces deceptive performance statistics, unrealistic drawdown estimates, and fatal sizing errors in production.
The continuous contract problem: How to stitch expiration cycles
Because individual futures contracts expire every month or quarter, multi-year quantitative research cannot be conducted on a single contract ticker (such as ESU24). Researchers must stitch successive contracts into a single synthetic continuous contract price series.
However, consecutive contracts rarely trade at identical prices at the moment of transition. The forward curve reflects the cost of carry (financing costs, storage costs, insurance, and convenience yield), placing deferred contracts at a premium (contango, where F_t > S_t) or a discount (backwardation, where F_t < S_t). Concatenating raw contracts without adjustment introduces synthetic price discontinuities at every roll boundary.
Unadjusted Roll Discontinuity:
Price ($)
 5,420 ┤                                        ╭── ESU24 (Expiring: 5,410)
 5,410 ┤                                  ╭─────╯
 5,400 ┤                                  │ <─── Artificial +15 pt Roll Gap Step!
 5,395 ┤                            ╭─────╯
 5,380 ┤                      ╭─────╯ (ESZ24 Deferred opens at 5,425)
       ┴──────────────────────┴──────────────────────────────────────> Time
If an unadjusted series jumps 15 index points overnight due solely to contract rollover, a moving average, RSI, or ATR indicator will interpret this administrative spread jump as genuine market momentum, generating phantom breakout signals.
1. The expiration cycle and roll timing
When building continuous series, determining the exact roll timestamp is critical:
- Calendar roll dates: Rolling on a predetermined calendar schedule (e.g., exactly 8 business days prior to contract expiration, or the 2nd Tuesday of the contract month). While predictable, calendar rolls can occur when liquidity is still concentrated in the expiring contract.
- Liquidity crossover rolls (Volume / Open Interest): Rolling on the first date where trading volume or open interest in the deferred (back-month) contract exceeds that of the prompt (front-month) contract. In CME equity index futures, this crossover typically occurs 6 to 8 calendar days prior to quarterly expiration (the Thursday or Friday preceding expiration week).
2. Stitching methodologies
Quant researchers utilize three primary continuous price adjustment algorithms:
A. Panama Canal adjustment (Cumulative difference adjustment)
The Panama Canal method aligns older contracts to the newest contract by subtracting the cumulative roll gap at each transition timestamp t_{\text{roll}, k}:
\Delta_k = P_{\text{new}}(t_{\text{roll}, k}) - P_{\text{old}}(t_{\text{roll}, k})P_{\text{adj}}(t) = P_{\text{raw}}(t) - \sum_{i=1}^{k} \Delta_i- Advantage: Preserves absolute point differences:
\Delta P_{\text{adj}} = \Delta P_{\text{raw}}. Dollar PnL on historical bars matches actual historical point moves dollar-for-dollar. - Disadvantage: In markets with persistent contango (e.g., Crude Oil or Natural Gas), subtracting cumulative roll premia backward over multi-year horizons can drive historical adjusted prices into negative values, breaking oscillators, percentage-based trailing stops, and logarithmic indicators.
B. Ratio / Proportional adjustment (Multiplicative adjustment)
The ratio method scales historical prices by the roll price ratio:
R_k = \frac{P_{\text{new}}(t_{\text{roll}, k})}{P_{\text{old}}(t_{\text{roll}, k})}P_{\text{adj}}(t) = P_{\text{raw}}(t) \times \prod_{i=1}^{k} \frac{1}{R_i}- Advantage: Preserves percentage returns and geometric price relations. Prices can never fall below zero, making it suitable for return-based indicators, volatility channels, and percentage indicators.
- Disadvantage: Distorts historical point volatility. A 10-point move in the S&P 500 ten years ago might be compressed into a 3-point move or inflated into a 30-point move, corrupting dollar-fixed stop distances and tick value calculations.
C. Unadjusted front-month (Raw concatenated series)
Raw concatenation splices the most liquid contract forward without shifting historical price levels.
- Advantage: Every historical bar reflects the actual, unaltered traded price at that timestamp.
- Disadvantage: Artificial step jumps at each roll timestamp distort technical indicators, trigger false stop losses, and artificially inflate historical volatility estimates.
Comparison of roll adjustment methods
| Stitching Method | Price Transformation | Indicator Integrity | PnL Tracking Accuracy | Recommended Use Case |
|---|---|---|---|---|
| Panama Canal (Difference) | Backward additive shift: P - \sum \Delta | Distorts ratio/percentage oscillators; can become negative | Exact dollar PnL: Point moves remain unwarped | Trend following and fixed-point stop systems |
| Ratio (Proportional) | Backward multiplicative scale: P \times \prod (1/R) | Preserves percentages: No negative prices | Distorts absolute point values in distant history | Momentum, RSI, and percentage volatility models |
| Unadjusted Front-Month | Raw contract splice: P_{\text{raw}} | Severely corrupted by artificial roll gap spikes | Flawed across roll boundaries | Short-term intraday models with positions closed daily |
[!IMPORTANT] Never optimize technical indicators across raw, unadjusted roll gaps. If testing a multi-month or multi-year strategy, use Panama Canal-adjusted series for dollar-invariant point stops, or Ratio-adjusted series for percentage-based indicators.
Point multipliers and cash PnL accounting
In spot equities, buying 100 shares of stock at 150 and selling at155 yields a profit of:
\text{PnL}_{\text{stock}} = 100 \times (\$155 - \$150) = \$500In futures contracts, price quotes are normalized units. Each point of price movement corresponds to a legally defined Point Multiplier (M):
\text{Gross PnL} = \text{Contracts} \times (P_{\text{exit}} - P_{\text{entry}}) \times MRepresentative contract specifications
| Contract Name | Exchange Ticker | Quoted Unit | Point Multiplier (M) | Minimum Tick | Tick Value ($) | Notional at Sample Price |
|---|---|---|---|---|---|---|
| E-mini S&P 500 | ES | Index Points | `50.00 | 0.25 pt | `12.50 | 5,400.00 pts = $270,000 |
| Micro E-mini S&P | MES | Index Points | `5.00 | 0.25 pt | `1.25 | 5,400.00 pts = $27,000 |
| E-mini Nasdaq 100 | NQ | Index Points | `20.00 | 0.25 pt | `5.00 | 19,500.00 pts = $390,000 |
| Light Sweet Crude Oil | CL | USD / Barrel | `1,000.00 | 0.01 pt | `10.00 | 75.00 / bbl =75,000 |
| 10-Year T-Note | ZN | Points (32nds) | `1,000.00 | 1/64 pt | `15.625 | 110.00 pts = $110,000 |
Modeling point multipliers in single-asset Python engines
Backtesting frameworks designed around linear unit accounting (where 1 unit of instrument represents 1 share with $$1 \Delta P = $1 \text{PnL}$) require disciplined mapping to represent futures.
In OpenBacktesting, order quantity represents the linear asset unit. To model an E-mini contract (M = 50) trading on a continuous price series:
\text{Order Qty} = \text{Contracts} \times \text{Point Multiplier}For example, buying 2 contracts of ES corresponds to qty = 2 * 50 = 100. When ES advances by 4 index points:
\text{Cash PnL} = 100 \times (+4.0) = \$400This matches the real-world futures PnL calculation: 2 \text{ contracts} \times 4.0 \text{ points} \times50/\text{point} = $400$.
Margin, leverage, and maintenance requirements
Futures trading operates on centralized performance bond requirements established by clearinghouses (such as CME Clearing) and adjusted by executing brokers:
- Initial Margin (IM): The minimum account equity required to open a new position. For ES, exchange initial margin is approximately $12,000 per contract (roughly 4.5% to 5% of total notional value).
- Maintenance Margin (MM): The minimum equity threshold that must remain in the account to keep an existing position open (typically 75% to 80% of Initial Margin).
- Intraday vs. Overnight Margin: Retail discount brokers frequently offer reduced "day-trading margins" (e.g., $500 per ES contract) for positions entered and exited within the same cash session. However, any position held across the daily exchange close (5:00 PM EST) requires full exchange overnight margin.
Account Equity vs. Maintenance Margin:

Account Equity ($)
 120k ┤  ╭──────────────╮
 100k ┤  │ Initial Cash │
  80k ┤  ╰───────╮      │
  60k ┤          ╰──────┴─────────────────╮
  40k ┤                                   │
  25k ┼───────────────────────────────────┼── Maintenance Margin Level
  20k ┤                                   ╰── Margin Call / Forced Broker Liquidation!
   0k ┴─────────────────────────────────────────────────────────────────────────────> Time
If mark-to-market losses push account equity below the maintenance margin threshold:
\text{Account Equity} = \text{Cash} + \text{Unrealized PnL} < \sum \text{Maintenance Margin}The broker issues a margin call or triggers an automatic algorithmic liquidation of open contracts at prevailing market prices, crystallizing losses.
In OpenBacktesting, setting margin = fraction (e.g., margin = 0.08 for an 8% initial margin requirement, or 12.5:1 leverage) enforces margin reservation. The engine blocks orders that exceed available purchasing power and incorporates leverage constraints into portfolio equity tracking.
Python implementation: Working with roll-adjusted futures series
The following self-contained script demonstrates how to backtest a trend-following Donchian Breakout strategy on a roll-adjusted continuous E-mini S&P 500 price series using OpenBacktesting.
The implementation models:
- Volatility-calibrated position sizing scaled by the $50 point multiplier.
- Initial margin constraints (
margin=0.08). - Fixed-point tick slippage (
Slippage("fixed", 0.25)). - Causal order matching at next-bar open (
execution_timing="next_open").
"""
Futures Trend Following Backtest on Continuous E-mini S&P 500 Series.
Models contract multipliers, margin reservation, and execution slippage.
"""

import numpy as np
import pandas as pd

from openbacktesting import Backtest, Strategy
from openbacktesting.broker.execution import Slippage
from openbacktesting.portfolio import export_result


def generate_synthetic_es_futures(n_bars: int = 600, seed: int = 42) -> pd.DataFrame:
    """Generate reproducible daily OHLCV series mimicking E-mini S&P 500 continuous futures."""
    np.random.seed(seed)
    dates = pd.date_range("2023-01-03", periods=n_bars, freq="B")

    # Generate synthetic drift and stochastic price movements
    drift = np.linspace(3850.0, 5200.0, n_bars)
    shocks = np.random.normal(0.0, 16.0, size=n_bars)
    close = drift + np.cumsum(shocks)

    # Synthetic intraday range and OHLC construction
    daily_range = np.abs(np.random.normal(30.0, 8.0, size=n_bars))
    high = close + daily_range * np.random.uniform(0.4, 0.7, size=n_bars)
    low = close - daily_range * np.random.uniform(0.4, 0.7, size=n_bars)
    open_ = low + (high - low) * np.random.uniform(0.2, 0.8, size=n_bars)
    volume = np.random.randint(1_200_000, 2_400_000, size=n_bars)

    # Quantize to CME 0.25 minimum tick increment
    high = np.round(high * 4) / 4
    low = np.round(low * 4) / 4
    open_ = np.round(open_ * 4) / 4
    close = np.round(close * 4) / 4

    # Enforce bar invariants
    high = np.maximum(high, np.maximum(open_, close))
    low = np.minimum(low, np.minimum(open_, close))

    return pd.DataFrame(
        {"Open": open_, "High": high, "Low": low, "Close": close, "Volume": volume},
        index=dates,
    )


class FuturesTrendFollowingStrategy(Strategy):
    """
    Donchian Breakout trend-following strategy calibrated for futures contracts.

    Execution logic:
    - Long entry when bar closes above 20-day rolling high.
    - Sizing: fixed 2% equity risk divided by (2 * ATR * Multiplier).
    - Hard stop-loss placed 2 * ATR below entry price.
    - Exit when bar closes below 10-day rolling low.
    """

    channel_period = 20
    exit_period = 10
    atr_period = 14
    risk_fraction = 0.02     # Risk 2% of account equity per trade
    point_multiplier = 50.0  # $50 per index point (CME E-mini S&P 500)
    atr_stop_multiple = 2.0  # Initial stop distance = 2.0 * ATR

    def init(self):
        """Precompute indicators across historical series."""
        # 20-day upper channel shifted causally by 1 bar to avoid lookahead bias
        self.upper_channel = self.ind(
            lambda h: pd.Series(h).rolling(self.channel_period).max().shift(1).to_numpy(),
            self.high,
        )
        # 10-day lower channel for trailing exits
        self.exit_channel = self.ind(
            lambda l: pd.Series(l).rolling(self.exit_period).min().shift(1).to_numpy(),
            self.low,
        )
        # Built-in ta.atr automatically consumes self.high, self.low, self.close
        self.atr = self.ta.atr(length=self.atr_period)

    def next(self):
        """Bar-by-bar execution logic."""
        # 1. Warm-up verification: ensure indicators have settled valid numbers
        if len(self.close) < self.channel_period + 2 or not self.atr.valid[-2:].all():
            return

        current_close = self.close[-1]
        current_atr = self.atr[-1]
        breakout_high = self.upper_channel[-1]
        exit_low = self.exit_channel[-1]

        # 2. Entry Logic
        if not self.position.is_long:
            if current_close > breakout_high:
                # Risk budget in dollars
                risk_capital = self.equity * self.risk_fraction

                # Dollar risk per contract = Point Stop Distance * Multiplier
                stop_distance_points = self.atr_stop_multiple * current_atr
                dollar_risk_per_contract = stop_distance_points * self.point_multiplier

                # Sizing in whole contracts
                contracts = max(1, int(risk_capital / dollar_risk_per_contract))

                # Order submission: Map to engine units (contracts * point_multiplier)
                stop_price = current_close - stop_distance_points
                self.buy(
                    qty=contracts * self.point_multiplier,
                    sl=stop_price,
                )

        # 3. Exit Logic: Trailing Donchian breakdown
        elif self.position.is_long:
            if current_close < exit_low:
                self.position.close()


def run_futures_audit():
    """Configure and execute the futures simulation with realistic execution parameters."""
    df = generate_synthetic_es_futures()
    print(f"Loaded {len(df)} ES futures bars ({df.index[0].date()} to {df.index[-1].date()})")

    # Configure Backtest engine with institutional futures parameters
    bt = Backtest(
        data=df,
        strategy=FuturesTrendFollowingStrategy,
        cash=250_000.0,                     # $250,000 initial equity
        margin=0.08,                        # ~12.5:1 leverage (8% initial margin requirement)
        commission=0.00005,                 # 0.5 bps transaction fee model
        slippage=Slippage("fixed", 0.25),   # 1 tick (0.25 index points) fixed slippage
        execution_timing="next_open",       # Orders match causally at next-bar open
        end_policy="close_at_last_close",   # Liquidate open position on final bar
    )

    stats = bt.run()

    # Print summary performance metrics
    print("\n" + "=" * 60)
    print("FUTURES STRATEGY BACKTEST RESULTS")
    print("=" * 60)

    report_metrics = [
        "Start",
        "End",
        "Duration",
        "Return [%]",
        "Sharpe Ratio",
        "Sortino Ratio",
        "Max. Drawdown [%]",
        "# Trades",
        "Win Rate [%]",
        "Profit Factor",
    ]

    for metric in report_metrics:
        val = stats.get(metric, "N/A")
        if isinstance(val, float):
            print(f"{metric:<24} : {val:>12.2f}")
        else:
            print(f"{metric:<24} : {str(val):>12}")

    # Inspect trade execution ledger
    trades = stats._trades
    print("\n" + "=" * 60)
    print(f"TRADE EXECUTION AUDIT (Total Trades: {len(trades)})")
    print("=" * 60)
    if not trades.empty:
        cols = ["EntryTime", "ExitTime", "Size", "EntryPrice", "ExitPrice", "PnL", "ReturnPct"]
        available_cols = [c for c in cols if c in trades.columns]
        print(trades[available_cols].head(5).to_string(index=False))

    # Export immutable Portfolio report schema for reproducible audit trails
    report = export_result(stats)
    print("\n" + "=" * 60)
    print(f"Audit Report exported successfully. Schema Version: {report.get('schemaVersion', 'v1')}")
    print("=" * 60)


if __name__ == "__main__":
    run_futures_audit()
Explanation of execution mechanics
- Multiplier Mapping (
qty = contracts * multiplier): Because OpenBacktesting executes on linear unit pricing, multiplying contract count by50 ensures every 1.0 point movement in price contributes exactly50 to dollar PnL, matching real-world CME accounting. - Fixed Tick Slippage (
Slippage("fixed", 0.25)): Futures orders fill across an electronic order book with discrete tick increments. For ES, 1 tick is 0.25 index points ($12.50). Using fixed slippage penalizes every fill by 1 tick, preventing optimistic mid-price execution. - Causal Next-Open Fills (
execution_timing="next_open"): Breakout signals generated at the close of bartfill at the open of bart+1, preserving strict temporal causality and avoiding lookahead bias. - Margin Modeling (
margin=0.08): Settingmargin=0.08reserves 8% collateral against notional exposure, ensuring purchasing power limits mirror broker requirements.
Realistic boundaries: Understanding engine capabilities
Quantitative rigor requires understanding both what your backtesting software proves and what falls outside its analytical scope.
What OpenBacktesting proves with mathematical precision
OpenBacktesting is an open-source Python framework engineered for single-asset historical OHLCV bar-by-bar backtesting. Within this defined scope, it deterministically guarantees:
- Strict Temporal Causality: Indicator warm-up periods are verified via
.validchecks, and signals generated at bartfill at bart+1without retrospective leakage. - Explicit Friction Accounting: Constant or basis-point slippage schedules and broker commission schedules are subtracted from the cash ledger on every fill.
- Deterministic Order Matching: Standard order primitives (market, limit, stop, stop-limit, trailing stop, and OCO) are matched against historical bar boundaries.
- Reproducible Audit Trails: Results can be exported into immutable Portfolio reports or inspected interactively via the local browser-based OpenBacktesting Studio.
Institutional futures realities managed upstream
While single-asset bar-by-bar simulation provides an essential filter for quantitative strategies, futures markets possess structural characteristics that require deliberate data engineering:
- No native contract roll calendar engine: OpenBacktesting operates on a pre-assembled continuous OHLCV time series. The researcher must stitch roll contracts (using Panama Canal difference or Ratio adjustment) in upstream ETL data pipelines prior to initiating the backtest.
- No native daily futures cash settlement engine: In live futures accounts, unrealized gains and losses are swept into cash every business day during the 4:15 PM CT settlement window (mark-to-market variation margin). In bar-by-bar backtesting, total account equity reflects mark-to-market performance accurately, but cash balance realizes when positions close.
- No native multi-asset portfolio accounting or SPAN margin offsets: CME SPAN (Standard Portfolio Analysis of Risk) grants substantial margin credits when holding correlated or offsetting positions across contracts (e.g., long ES vs. short NQ, or calendar inter-month spreads). Single-asset engines model positions independently without portfolio-level cross-margining.
- Delivery and notice day blackouts: Strategies holding physical-delivery contracts (such as Crude Oil, Copper, or Agricultural commodities) must enforce hard programmatic exits prior to First Notice Day (FND) to avoid physical delivery obligations.
[!NOTE] OpenBacktesting focuses exclusively on single-asset historical research and parameter optimization (grid search and SAMBO). It does not provide live-trading broker APIs, real-time data feeds, or low-latency execution routing.
Summary checklist for futures backtesting
Before deploying capital into algorithmic futures strategies, verify your model against this 6-point practitioner's audit checklist:
| Audit Item | Potential Vulnerability | Mandatory Verification Action |
|---|---|---|
| 1. Continuous Roll Stitching | Raw contract concatenation causes artificial gap spikes that trigger false breakouts and corrupt ATR. | Stitch continuous series using Panama Canal adjustment (for fixed-point stops) or Ratio adjustment (for percentage indicators). |
| 2. Multiplier Scaling | Treating contract count as raw share units understates dollar risk and PnL by factor of M. | Scale order quantity by the point multiplier (qty = contracts * multiplier) so dollar PnL aligns with CME specifications. |
| 3. Discrete Tick Slippage | Assuming fill at exact stop price ignores tick granularity and book depth. | Apply at least 1 full tick of fixed slippage (Slippage("fixed", tick_size)) on liquid contracts, and 2–4 ticks on illiquid contracts. |
| 4. Overnight Margin Reservation | Underestimating margin requirements risks broker liquidation during drawdown. | Calibrate margin = fraction to reflect exchange overnight margin (typically 5%–10%), rather than day-trading broker discounts. |
| 5. Causal Order Matching | Evaluating indicators and executing within the same bar introduces lookahead bias. | Enforce execution_timing="next_open" so signals at bar t close fill strictly at bar t+1 open. |
| 6. Delivery Blackout Rule | Holding physical-delivery contracts past First Notice Day triggers physical delivery risk. | Enforce an explicit calendar exit rule at least 5 business days prior to First Notice Day (FND) or Last Trading Day (LTD). |
Conclusion and resources
Backtesting futures contracts requires transcending basic cash-equity assumptions. By properly stitching continuous series, scaling positions by contract point multipliers, modeling exchange overnight margins, and enforcing discrete tick slippage, you turn theoretical backtests into durable, production-ready trading models.
To continue building your quantitative research framework, explore these foundational guides:
- End-to-End Implementation: Master data ingestion, strategy callbacks, and trade inspection in our Python Backtesting Tutorial: Data, Orders and Results.
- Foreign Exchange Microstructure: Contrast centralized futures execution with decentralized currency markets in our guide on Forex Backtesting: Spreads, Sessions and Execution Assumptions.
- Official Documentation: Review engine parameters, execution timing models, and optimization workflows in the OpenBacktesting Documentation.