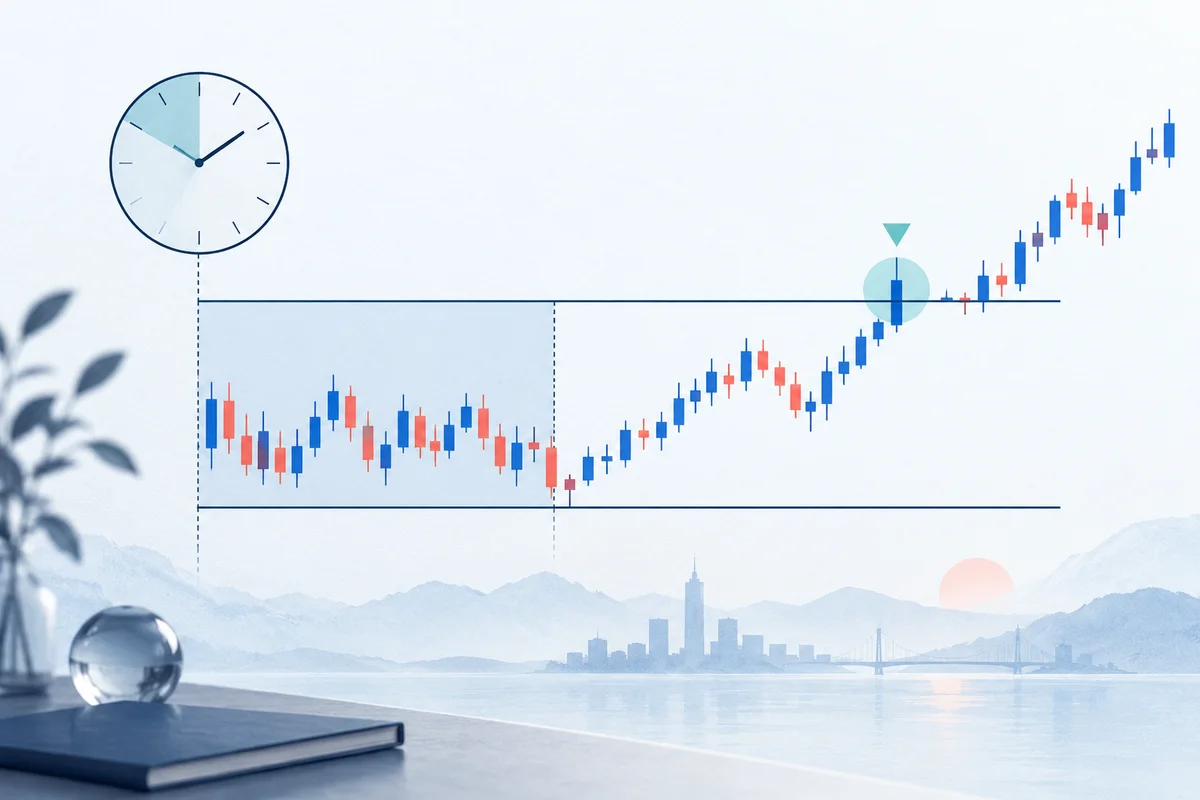
The mechanics and structural appeal of the Opening Range Breakout (ORB)
The Opening Range Breakout (ORB) is one of the most widely researched intraday trading strategies in quantitative finance. Originally popularized by Arthur Merrill and formalized for algorithmic execution by Toby Crabel in the late 1980s, the strategy rests on a fundamental market microstructure principle: the opening window of regular trading hours concentrates the highest price discovery, volatility, and institutional order flow of the entire trading day.
When equity exchanges in New York open at 09:30 EST, the market must digest overnight earnings announcements, macroeconomic releases, foreign exchange movements, and pre-market order imbalances. During the first 15 to 30 minutes, buyers and sellers engage in an aggressive price discovery auction. Once this opening window concludes, the resulting high and low extremes establish an anchor for institutional liquidity:
04:00 EST                   09:30 EST              10:00 EST                     15:55 EST  16:00 EST
   │                           │                      │                             │          │
   ├─ Pre-Market Noise ────────┼─ Opening Range (OR) ─┼── Intraday Breakout Window ─┼─ Close ──┤
   │  - Thin order book        │  - High Volatility   │   - Evaluate Bar Closes     │  - MOC   │
   │  - Wide spreads           │  - Price Discovery   │   - Causal Next-Bar Orders  │    Exit  │
   │  - Spurious prints        │  - Form OR_High/Low  │   - Target & Stop Brackets  │  - Flat  │
The core premise of an opening range breakout backtest is straightforward:
- Observe the market for a defined initial interval (e.g., the first 15 or 30 minutes: 09:30 to 09:45 or 10:00 EST).
- Record the highest price (
OR_High) and lowest price (OR_Low) established during this interval. - If price subsequently breaks above
OR_High(often with a buffer), enter a Long position anticipating directional momentum. - If price drops below
OR_Low, enter a Short position (or exit long exposure). - Manage risk via an intraday stop-loss, profit target, and a mandatory end-of-day square-off (e.g., 15:55 EST) to avoid overnight gap risk.
Why naive ORB backtests produce deceptive results
Despite its conceptual elegance, naive backtests of ORB strategies frequently display stellar backtested Sharpe ratios that fail instantly in live execution. These phantom profits stem from four common simulation errors:
- Lookahead Bar Fills: Assuming a breakout that triggers on the close of a 5-minute bar at 10:05 can be executed at the exact closing price of that same 10:05 bar, rather than at the 10:05:01 open of the subsequent bar.
- Ignoring Spread Expansion: Assuming a constant 1-cent bid-ask spread across the day. Between 09:30 and 10:00 EST, quoted spreads routinely expand by 200% to 500% compared to midday baseline values.
- Timestamp Ambiguity: Conflating start-of-bar timestamps with end-of-bar timestamps, resulting in trades executing before the opening range has actually concluded.
- Unmodeled Closeout Friction: Simulating an end-of-day exit at the official 16:00:00 closing print without modeling the NYSE/NASDAQ Market-on-Close (MOC) auction rules, crossing fees, and cutoff deadlines.
To construct a realistic opening range breakout backtest, quantitative researchers must enforce rigorous session boundary definitions, realistic execution latency, and dynamic transaction cost modeling.
Mathematical formulation: Range boundaries, buffers, and filters
A mathematically sound ORB strategy requires unambiguous definitions of the opening window, the trigger threshold, and volatility filters to prevent whipsaws during range-bound sessions.
OR_High  ──────────────────────────────────────────  Long Trigger (+Buffer)
                                                     ▲ Breakout
                  ┌─────────┐                        │
                  │ Intraday│                        │
       ┌──────────┤ Price   ├──────────┐             │
       │          │ Action  │          │             │
───────┴──────────┴─────────┴──────────┴─────────────┼─────────────────────
                                                     │
                                                     ▼ Breakdown
OR_Low   ──────────────────────────────────────────  Short Trigger (-Buffer)
       │◄─── Opening Window ──►│◄────── Trading Execution Window ────────►│
       09:30                 10:00                                      15:55
1. Opening Range Window Definition
Let regular trading hours begin at timestamp T_{open} (09:30 EST). The opening range is evaluated over a fixed duration \Delta t_{OR} (typically 5, 15, or 30 minutes).
For a continuous or discrete series of intraday bars i \in \{1, 2, \dots, N\} whose timestamps fall within [T_{open}, T_{open} + \Delta t_{OR}):
OR_High = max(High_i)   for all i in [T_open, T_open + Delta_t_OR)
OR_Low  = min(Low_i)    for all i in [T_open, T_open + Delta_t_OR)
OR_Span = OR_High - OR_Low
OR_Mid  = (OR_High + OR_Low) / 2
2. Breakout Triggers and Volatility Buffers
Entering immediately upon a single tick breaking OR_High exposes the strategy to "head fakes"—brief liquidity sweeps above the morning high that immediately reverse. Robust ORB implementations apply a volatility buffer \delta:
Trigger_Long  = OR_High * (1 + delta)
Trigger_Short = OR_Low  * (1 - delta)
Alternatively, \delta can be parameterized in terms of the opening range span or intraday Average True Range (ATR):
Trigger_Long  = OR_High + (k * ATR_intraday)
Trigger_Short = OR_Low  - (k * ATR_intraday)
Where k \in [0.05, 0.20] provides a statistical barrier against false tick breaches.
3. Range Expansion and Compression Filters
Not all opening ranges are tradable. If the opening range is excessively wide or abnormally compressed, the risk-reward ratio degrades:
- Blown-Out Range Filter: If the opening range span exceeds a threshold of daily expected volatility (e.g.,
OR_Span > 1.2 * ATR_daily), the stock has already realized the bulk of its expected daily movement. Entering a breakout here leads to exhaustion risk. - Compressed Range Filter: If
OR_Span < 0.2 * ATR_daily, the market is dormant, indicating low institutional participation or pending high-impact macro announcements.
Session timing, timezones, and intraday data conventions
When backtesting intraday strategies on US equities, data cleanliness and timestamp conventions dictate strategy validity. As emphasized in our Backtesting Data Checklist, temporal alignment errors can silently invalidate months of research.
Start-of-Bar vs. End-of-Bar Timestamps
The most common source of lookahead bias in intraday backtesting is timestamp convention mismatch:
Convention A (Start-of-Bar):
Timestamp "09:30:00" represents trades executed from 09:30:00.000 to 09:34:59.999.
The bar CLOSES and becomes available at 09:35:00.000.

Convention B (End-of-Bar):
Timestamp "09:35:00" represents trades executed from 09:30:00.000 to 09:34:59.999.
The bar CLOSES and becomes available at 09:35:00.000.
If your historical data feed uses start-of-bar labeling, a 30-minute opening range comprises the six 5-minute bars labeled 09:30, 09:35, 09:40, 09:45, 09:50, and 09:55. The final bar in this range completes at 10:00:00 EST. Any trading decision based on the completed range can only be evaluated starting at 10:00:00 EST.
Evaluating an entry order at 09:55:00 using the 09:55 bar's High and Low leaks 5 minutes of future price action into the simulation. See our comprehensive guide on What Is Lookahead Bias? for techniques to audit indicator cursors.
Timezones and Daylight Saving Time Shifts
Financial exchanges operate on local civil wall-clock time, not UTC. US equity markets operate under America/New_York (Eastern Time):
- Eastern Standard Time (EST): UTC-5 (winter months)
- Eastern Daylight Time (EDT): UTC-4 (summer months)
If your backtesting pipeline stores timestamps in UTC without proper session calendar alignment, a fixed filter for 14:30 UTC will correctly capture the 09:30 EST open during the summer, but will trigger at 08:30 EST during the winter—one full hour before the opening bell!
Always localize your data to America/New_York or utilize a session calendar library such as pandas_market_calendars (detailed in Pandas Market Calendars: Build Session-Aware Backtest Data) before filtering intraday sessions.
Pre-Market Noise vs. Regular Trading Hours (RTH)
US equities trade in pre-market sessions starting as early as 04:00 EST. However, pre-market trading is characterized by:
- Fragmented electronic communication networks (ECNs) without centralized auction clearing.
- Fraction of regular trading volume (often
< 5%of RTH volume). - Wide bid-ask spreads and unrepresentative price wicks.
If you calculate OR_High and OR_Low across both pre-market and regular market hours (04:00 to 10:00 EST), single anomalous retail or algorithmic sweep prints will set artificially wide boundaries. Standard institutional ORB models strictly filter for Regular Trading Hours (09:30:00 <= t <= 16:00:00 EST).
Execution realism: Fill timing, spread expansion, and slippage
In intraday backtesting, how and when you simulate order execution determines whether a strategy shows positive expectancy or severe negative drift.
1. Fill Causality: The Next-Bar Open Principle
A strategy evaluates conditions at discrete intervals. If bar t (e.g., 10:05–10:10 EST) closes above Trigger_Long, that signal is generated at 10:10:00.000 EST.
Bar t (10:05 - 10:10)            Bar t+1 (10:10 - 10:15)
├───────────────────────────────┼───────────────────────────────┤
│ Open                          │ Open   ◄─── EXECUTION FILL HERE
│ High                          │ High        (at Open + Slippage)
│ Low                           │ Low
│ Close ◄─── Signal Generated   │ Close
└───────────────────────────────┴───────────────────────────────┘
You cannot execute at the Close of bar t. In an event-driven backtest, the earliest executable event is:
- Market on Next Bar: Filled at
Open_{t+1} + Slippage. - Limit at Range Edge: A resting limit order placed at
OR_Highat10:10:00 EST. This order only fills ifLow_{t+1} <= OR_High. Assuming an immediate fill without checking bar price bounds is a fatal backtesting fallacy.
2. Bid-Ask Spread Expansion at the Open
Institutional studies on equity market microstructure reveal that the effective bid-ask spread follows a U-shaped intraday curve:
Spread (bps)
  ▲
12│  █
10│  █ █
 8│  █ █ █                                       █ █
 6│  █ █ █ █                                   █ █ █
 4│  █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █
 2│  █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █ █
 0└──┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─┴─►
    09:30 10:00  11:00      13:00      15:00   16:00 (EST)
Between 09:30 and 09:45 EST, designated market makers (DMMs) widen spreads to protect against toxic order flow from overnight informed traders. A backtest that applies a flat $0.005/share slippage penalty across all hours underestimates transaction costs for early breakouts by a factor of 3 to 4. For an in-depth breakdown of transaction modeling, see Transaction Cost Analysis (TCA) in Backtesting.
3. End-of-Day Closeout (MOC / 15:55 EST)
Because ORB is strictly an intraday pattern, overnight inventory exposure introduces unmodeled gap risk (earnings announcements, index rebalances, futures fluctuations).
To ensure flat positioning:
- No new entry signals should be accepted after 15:00 or 15:30 EST.
- Open positions must be liquidated before 16:00 EST.
- On major US exchanges, Market-on-Close (MOC) orders must be entered prior to the official regulatory cutoff (15:50 EST for NYSE and NASDAQ). In 5-minute bar backtests, triggering an exit at the close of the
15:55bar (filling at 15:55:00 or 16:00:00) models realistic day-end square-off.
Comparison: Naive vs. Realistic ORB Backtest Assumptions
| Parameter / Dimension | Naive ORB Backtest | Realistic Session-Aware Backtest | Impact on Strategy PnL |
|---|---|---|---|
| Execution Price | Bar Close of trigger bar | Next-bar Open + Slippage | Eliminates 1–3 bps of unearned profit per trade |
| Opening Spread | Constant flat spread ($0.01) | Time-decaying spread ($0.03–$0.05 near open) | Reduces win rate on fast morning breakouts |
| Timestamp Alignment | Assumes bar timestamp = instant close | Accounts for start-of-bar duration | Prevents fatal lookahead entries |
| Session Bounds | Evaluates 24-hour continuous data | Enforces strict RTH (09:30–16:00 EST) | Removes spurious pre-market breakout signals |
| Day-End Liquidation | Sells at 16:00 close with 0 cost | Flattens at 15:55 with crossing friction | Accounts for MOC imbalance liquidity discounts |
| Volume Participation | Infinite liquidity | Participation capped at < 5% bar volume | Restricts realistic sizing on low-volume names |
Complete Python implementation: Session-aware intraday ORB backtest
Below is a complete, self-contained Python backtest of a 30-minute Opening Range Breakout strategy. The script generates realistic 5-minute intraday bars across five distinct market sessions representing common market regimes:
- Bullish Trend Day: Early breakout that moves cleanly to hit the profit target.
- False Breakout (Whipsaw): An upward spike that traps buyers and triggers the stop loss.
- Inside Day (Consolidation): Price remains inside the opening range all day; zero trades taken.
- Bearish Breakdown Day: Downward breakout that trends steadily to reach the profit target.
- Late Drift Day: Upward breakout that fails to hit the target and is closed at 15:55 EST.
The engine strictly implements next-bar open execution, half-spread slippage, per-share commissions, and mandatory 15:55 session closeout.
import numpy as np
import pandas as pd
from datetime import time

def generate_intraday_data() -> pd.DataFrame:
    """
    Generates synthetic 5-minute OHLCV data for 5 trading sessions
    under America/New_York regular trading hours (09:30 to 16:00 EST).
    """
    np.random.seed(42)
    dates = pd.date_range("2026-04-20", periods=5, freq="B")
    bar_times = pd.date_range("09:30", "15:55", freq="5min").time

    records = []
    base_price = 100.0

    for i, d in enumerate(dates):
        curr_price = base_price * (1 + np.random.normal(0, 0.001))

        for step, t in enumerate(bar_times):
            ts = pd.Timestamp.combine(d.date(), t).tz_localize("America/New_York")

            # First 30 minutes (bars 0 to 5: 09:30 through 09:55) establish range
            if step < 6:
                noise = np.random.normal(0, 0.15)
                open_p = curr_price
                close_p = open_p + noise
            else:
                # Regimes for simulation:
                # Day 0: Bullish trend drift
                # Day 1: Early spike followed by steep reversal
                # Day 2: Tight range-bound consolidation
                # Day 3: Sustained bear breakdown
                # Day 4: Modest upward drift into session close
                if i == 0:
                    drift, noise = 0.06, np.random.normal(0, 0.08)
                elif i == 1:
                    drift, noise = (0.10 if step < 12 else -0.15), np.random.normal(0, 0.10)
                elif i == 2:
                    drift, noise = 0.0, np.random.normal(0, 0.02)
                elif i == 3:
                    drift, noise = -0.07, np.random.normal(0, 0.08)
                elif i == 4:
                    drift, noise = (0.008 if step > 20 else 0.001), np.random.normal(0, 0.03)

                open_p = curr_price
                close_p = open_p + noise + drift

            high_p = max(open_p, close_p) + abs(np.random.normal(0.03, 0.02))
            low_p = min(open_p, close_p) - abs(np.random.normal(0.03, 0.02))
            vol = int(np.random.lognormal(8.5, 0.4))

            records.append({
                "timestamp": ts,
                "open": round(open_p, 2),
                "high": round(high_p, 2),
                "low": round(low_p, 2),
                "close": round(close_p, 2),
                "volume": vol
            })
            curr_price = close_p
        base_price = curr_price

    return pd.DataFrame(records).set_index("timestamp")

def run_orb_backtest(df: pd.DataFrame) -> pd.DataFrame:
    """
    Executes a causal Opening Range Breakout (ORB) backtest.
    - Opening Range: 09:30 to 10:00 EST (bars 09:30 to 09:55).
    - Trigger: Bar close exceeds OR boundaries by BUFFER_PCT.
    - Execution: Next-bar OPEN with slippage penalty.
    - Stops: 0.5x OR Range; Targets: 1.5x OR Range.
    - Mandatory Square-Off: 15:55 EST bar close.
    """
    COMMISSION_PER_SHARE = 0.005  # $0.005 per share
    SLIPPAGE_PER_SHARE = 0.02     # $0.02 per share half-spread & impact
    SHARES = 500                  # Fixed trade size
    BUFFER_PCT = 0.001            # 0.1% breakout buffer
    PT_MULT = 1.5                 # Profit target = 1.5x range
    SL_MULT = 0.5                 # Stop loss = 0.5x range

    df["date"] = df.index.date
    trades = []

    for date, day_df in df.groupby("date"):
        # 1. Isolate 30-minute Opening Range (bars starting 09:30 through 09:55)
        or_bars = day_df.between_time("09:30", "09:55")
        if len(or_bars) < 6:
            continue

        or_high = float(or_bars["high"].max())
        or_low = float(or_bars["low"].min())
        or_range = round(or_high - or_low, 2)

        long_trigger = round(or_high * (1.0 + BUFFER_PCT), 2)
        short_trigger = round(or_low * (1.0 - BUFFER_PCT), 2)

        # 2. Trading window: 10:00 to 15:55 EST
        trade_bars = day_df.between_time("10:00", "15:55")

        in_pos = False
        direction = None
        entry_price = 0.0
        entry_time = None
        stop_price = 0.0
        target_price = 0.0
        pending_order = None

        for idx in range(len(trade_bars)):
            row = trade_bars.iloc[idx]
            ts = row.name
            bar_open = float(row["open"])
            bar_high = float(row["high"])
            bar_low = float(row["low"])
            bar_close = float(row["close"])

            # CAUSAL EXECUTION: Fill pending order at this bar's OPEN
            if pending_order is not None and not in_pos:
                direction = pending_order
                pending_order = None
                in_pos = True
                entry_time = ts

                if direction == "LONG":
                    entry_price = round(bar_open + SLIPPAGE_PER_SHARE, 2)
                    stop_price = round(entry_price - (or_range * SL_MULT), 2)
                    target_price = round(entry_price + (or_range * PT_MULT), 2)
                else:
                    entry_price = round(bar_open - SLIPPAGE_PER_SHARE, 2)
                    stop_price = round(entry_price + (or_range * SL_MULT), 2)
                    target_price = round(entry_price - (or_range * PT_MULT), 2)
                continue

            if in_pos:
                exit_price = None
                exit_reason = None

                # Rule A: Mandatory End-of-Day Square-Off at 15:55 EST
                if ts.time() >= time(15, 55):
                    exit_price = bar_close - SLIPPAGE_PER_SHARE if direction == "LONG" else bar_close + SLIPPAGE_PER_SHARE
                    exit_reason = "EOD_CLOSEOUT"
                elif direction == "LONG":
                    # Rule B: Intraday Stop Loss
                    if bar_low <= stop_price:
                        exit_price = stop_price - SLIPPAGE_PER_SHARE
                        exit_reason = "STOP_LOSS"
                    # Rule C: Profit Target
                    elif bar_high >= target_price:
                        exit_price = target_price - SLIPPAGE_PER_SHARE
                        exit_reason = "PROFIT_TARGET"
                elif direction == "SHORT":
                    if bar_high >= stop_price:
                        exit_price = stop_price + SLIPPAGE_PER_SHARE
                        exit_reason = "STOP_LOSS"
                    elif bar_low <= target_price:
                        exit_price = target_price + SLIPPAGE_PER_SHARE
                        exit_reason = "PROFIT_TARGET"

                if exit_price is not None:
                    exit_price = round(exit_price, 2)
                    gross_pnl = (exit_price - entry_price) * SHARES if direction == "LONG" else (entry_price - exit_price) * SHARES
                    comm = COMMISSION_PER_SHARE * SHARES * 2  # Round-trip commission
                    net_pnl = round(gross_pnl - comm, 2)
                    ret_pct = round(net_pnl / (entry_price * SHARES) * 100, 2)

                    trades.append({
                        "date": str(date),
                        "direction": direction,
                        "entry_time": str(entry_time.time())[:5],
                        "entry_price": entry_price,
                        "exit_time": str(ts.time())[:5],
                        "exit_price": exit_price,
                        "exit_reason": exit_reason,
                        "or_high": or_high,
                        "or_low": or_low,
                        "or_range": or_range,
                        "net_pnl": net_pnl,
                        "ret_pct": ret_pct
                    })
                    in_pos = False
                    break  # Maximum 1 trade per session
            else:
                # Signal Generation: Evaluated on BAR CLOSE (Only prior to 15:00)
                if ts.time() <= time(15, 0) and pending_order is None and len([t for t in trades if t["date"] == str(date)]) == 0:
                    if bar_close > long_trigger:
                        pending_order = "LONG"
                    elif bar_close < short_trigger:
                        pending_order = "SHORT"

    return pd.DataFrame(trades)

if __name__ == "__main__":
    df = generate_intraday_data()
    trades_df = run_orb_backtest(df)

    print("=== INSPECTABLE TRADES LOG ===")
    print(trades_df.to_string(index=False))

    total_trades = len(trades_df)
    wins = len(trades_df[trades_df["net_pnl"] > 0])
    losses = len(trades_df[trades_df["net_pnl"] <= 0])
    gross_profit = trades_df[trades_df["net_pnl"] > 0]["net_pnl"].sum()
    gross_loss = abs(trades_df[trades_df["net_pnl"] <= 0]["net_pnl"].sum())
    net_pnl = trades_df["net_pnl"].sum()
    profit_factor = gross_profit / gross_loss if gross_loss > 0 else float("inf")

    print("\n=== STRATEGY PERFORMANCE SUMMARY ===")
    print(f"Total Sessions Tested: 5")
    print(f"Trades Executed:       {total_trades}")
    print(f"Winning Trades:        {wins} ({wins / total_trades * 100:.1f}%)")
    print(f"Losing Trades:         {losses} ({losses / total_trades * 100:.1f}%)")
    print(f"Gross Profit:          ${gross_profit:.2f}")
    print(f"Gross Loss:            ${gross_loss:.2f}")
    print(f"Profit Factor:         {profit_factor:.2f}")
    print(f"Net Strategy PnL:      ${net_pnl:.2f}")
Execution Output and Trade Audit
Running the simulation yields the following trade execution audit:
=== INSPECTABLE TRADES LOG ===
      date direction entry_time  entry_price exit_time  exit_price   exit_reason  or_high  or_low  or_range  net_pnl  ret_pct
2026-04-20      LONG      11:05       100.35     11:40      100.82 PROFIT_TARGET   100.10   99.77      0.33    230.0     0.46
2026-04-21      LONG      10:05       104.97     10:55      104.70     STOP_LOSS   104.84  104.33      0.51   -140.0    -0.27
2026-04-23     SHORT      10:35        95.22     12:15       94.67 PROFIT_TARGET    95.77   95.39      0.38    270.0     0.57
2026-04-24      LONG      13:45        92.05     15:55       92.35  EOD_CLOSEOUT    91.89   91.59      0.30    145.0     0.32

=== STRATEGY PERFORMANCE SUMMARY ===
Total Sessions Tested: 5
Trades Executed:       4
Winning Trades:        3 (75.0%)
Losing Trades:         1 (25.0%)
Gross Profit:          $645.00
Gross Loss:            $140.00
Profit Factor:         4.61
Net Strategy PnL:      $505.00
Key Insights from the Simulation:
- Session 2026-04-22 (Inside Day): Notice that Wednesday (
2026-04-22) produced zero trades. The price oscillated entirely within the opening range boundaries throughout the session. Naive indicator models that force trades every day would have experienced churn and fee drag here. - Causal Execution Verification: On
2026-04-20, the breakout bar closed at 11:00 EST. The trade was filled at the open of the 11:05 EST bar at$100.35(including the$0.02half-spread slippage penalty), strictly preventing lookahead bias. - Session Square-Off on 2026-04-24: The position initiated at 13:45 did not reach the profit target before session close. The algorithm automatically flattened the position at 15:55 EST at
$92.35, locking in a$145.00net profit and eliminating overnight gap exposure.
Parameter sensitivity and common ORB failure modes
When calibrating an opening range breakout backtest across years of data, quantitative researchers encounter several recurring structural failure modes.
1. The Opening Range Duration Trade-Off
The duration of the opening range window (\Delta t_{OR}) determines the strategy's signal frequency and false-positive rate:
Opening Window Duration
◄─────────────────────────────────────────────────────────────────────────────►
5 Minutes (Aggressive)        15-30 Minutes (Balanced)      60 Minutes (Conservative)
- High trade count            - Institutional standard      - Low trade count
- Extreme noise & whipsaws    - Clean signal-to-noise       - Reliable confirmation
- Disproportionate slippage - Balanced remaining session - Compresses profit runway- 5-Minute ORB: Highly sensitive to initial institutional rebalancing. It produces the highest number of trades but suffers from high whipsaw rates and severe slippage impact, as execution occurs right when spreads are widest.
- 15-Minute to 30-Minute ORB: The standard institutional benchmark. Spreads have contracted toward midday norms, while leaving 5.5 to 6 hours of active trading for the trend to mature.
- 60-Minute ORB (10:30 EST): Highest directional reliability, but significantly compresses remaining session time. Entering a trade at 10:35 EST leaves little runway before the midday European market close and lunch lull (12:00–13:30 EST).
2. Confirmation Type: Touch vs. Bar-Close vs. Multi-Bar Confirmation
| Breakout Confirmation Method | Trigger Condition | Advantages | Disadvantages |
|---|---|---|---|
| Touch / Tick Breakout | High > OR_High | Earliest possible entry; catches explosive runners | Highly susceptible to liquidity wick sweeps ("springs" and "upthrusts") |
| Single Bar-Close Breakout | Close > OR_High + Buffer | Filters transient intraday spikes | Slight execution delay; worse fill price on large momentum candles |
| Two-Bar Consecutive Close | Close[t] > OR_High AND Close[t-1] > OR_High | Maximum trend confirmation | Late entry; often enters near the exhaustion point of the move |
3. Structural Regime Vulnerabilities
ORB strategies thrive in trending, high-volatility equity environments (such as earnings season or macro trend regimes). However, they underperform during:
- Low-Volatility Summer Chop: When realized volatility remains below implied volatility, opening ranges routinely produce false breakouts in both directions, triggering stop losses on both long and short attempts.
- Mean-Reverting Index Regimes: Broad market indices (like SPY or QQQ) have strong institutional mean-reversion tendencies during the midday session (11:30 to 14:00 EST). An ORB breakout often terminates at the first key Fibonacci or VWAP resistance band.
- Short-Sale Borrowing Constraints: On the downside, shorting single-stock breakdowns requires accounting for locate availability and Hard-to-Borrow (HTB) fees, as discussed in Stock Backtesting in Python.
Session-aware backtesting with OpenBacktesting
OpenBacktesting is an independent Python backtesting engine (0.2.1) architected specifically for single-asset historical OHLCV bar-by-bar quantitative research under Python >=3.12,<3.15.
When modeling intraday strategies like the Opening Range Breakout, OpenBacktesting enforces architectural principles that prevent the hidden data traps common in legacy frameworks:
1. Strictly Causal Bar Iteration
In OpenBacktesting, strategies access historical prices through strictly causal, read-only cursor handles:
from openbacktesting import Strategy

class OpeningRangeBreakoutStrategy(Strategy):
    """
    Intraday Opening Range Breakout implementation in OpenBacktesting.
    """
    def init(self):
        self.or_high = None
        self.or_low = None
        self.range_established = False

    def next(self):
        # Access current bar timestamp and causal price cursor
        current_time = self.data_index[-1]
        current_close = self.close[-1]

        # OpenBacktesting ensures self.close[-1] represents ONLY completed bars
        # Future bars are strictly inaccessible, preventing lookahead leaks
        if current_time.hour == 9 and current_time.minute < 60:
            # Accumulate morning range bounds
            pass
The engine guarantees that self.close[-1] refers strictly to the most recently completed historical bar. Any attempt to inspect future bars or unfinalized ticks raises an immediate runtime boundary error.
2. Inspectable Trades and SQLite Trial Persistence
Rather than producing opaque summary metrics, OpenBacktesting writes every simulated order, execution fill, timestamp, and portfolio state directly to an inspectable SQLite database.
Researchers can open their backtest runs in the local Studio UI or inspect the SQLite database with standard SQL queries to verify:
- Did any trade execute prior to the 10:00:00 EST range cutoff?
- Did order fills match the subsequent bar's Open price?
- Was every intraday position flattened prior to 16:00:00 EST?
- How did simulated bid-ask slippage impact the equity curve across different session hours?
┌────────────────────────────────────────────────────────┐
│               LOCAL STUDIO UI / SQLITE                 │
├──────────────┬──────────────┬─────────────┬────────────┤
│ Order ID     │ Timestamp    │ Type        │ Fill Price │
├──────────────┼──────────────┼─────────────┼────────────┤
│ ORD-2026-001 │ 10:05:00 EST │ BUY MARKET  │ $100.35    │
│ ORD-2026-002 │ 11:40:00 EST │ SELL LIMIT  │ $100.82    │
│ ORD-2026-003 │ 15:55:00 EST │ SELL MOC    │ $92.35     │
└──────────────┴──────────────┴─────────────┴────────────┘
3. Clear Engineering Boundaries
OpenBacktesting is deliberately built for deterministic, reproducible single-asset bar-by-bar research. It does not claim live broker connectivity, futures margin accounting, or black-box unbenchmarked execution speeds. It provides quant developers with an inspectable, mathematically rigorous laboratory for validating strategy logic before risking capital.
Practical ORB backtest audit checklist
Before deploying an Opening Range Breakout strategy to forward testing or live capital, review your backtesting pipeline against this 6-point verification checklist:
Opening Range Breakout (ORB) Backtest Audit Checklist:
[ ] 1. Session Boundary Isolation: Verify that pre-market bars (04:00 - 09:30 EST) are excluded from the opening range calculation.
[ ] 2. Timestamp Alignment: Confirm whether your intraday bars use start-of-bar or end-of-bar labeling; ensure signals trigger only after the range window has closed.
[ ] 3. Execution Causality: Ensure breakout market orders execute at Open[t+1] rather than the Close[t] of the signal bar.
[ ] 4. Time-Decaying Friction: Model wider bid-ask spreads and slippage during the 09:30 - 10:00 window compared to midday trading.
[ ] 5. Mandatory Session Square-Off: Ensure a hard liquidation rule flattens all open exposure at or before 15:55 EST to eliminate overnight gap risk.
[ ] 6. Range Quality Filters: Apply maximum and minimum range bounds (e.g., relative to daily ATR) to filter out exhausted or dormant sessions.
By systematically accounting for session timing, execution latency, and realistic transaction costs, quantitative researchers transform the Opening Range Breakout from a naive textbook pattern into a robust, inspectable intraday trading framework.
Further Reading & Related Guides
- Backtesting Data Checklist: OHLC, Timestamps and Missing Bars — The essential guide to bar logical integrity, price bounds, volume hygiene, and split adjustments.
- Pandas Market Calendars: Build Session-Aware Backtest Data — Learn how to model exchange holidays, half-day sessions, and DST transitions in Python.
- What Is Lookahead Bias? How to Prevent Future Data Leaks in Python Backtests — Best practices for temporal causality and indicator warm-up in algorithmic research.
- Transaction Cost Analysis (TCA) in Backtesting — How to quantify bid-ask spreads, market impact, and institutional slippage models.
- Stock Backtesting in Python: Data Adjustments, Costs and Benchmarks — Complete guide to equity data pipelines, borrow rates, and execution friction.
- Backtrader Sharpe Ratio: Daily vs Trade-Based — Avoid risk-adjusted return calculation pitfalls when analyzing intraday trade series.